Friday was a tug of war, and the bond market came out of it with a win for the week anyway.
How Friday played out
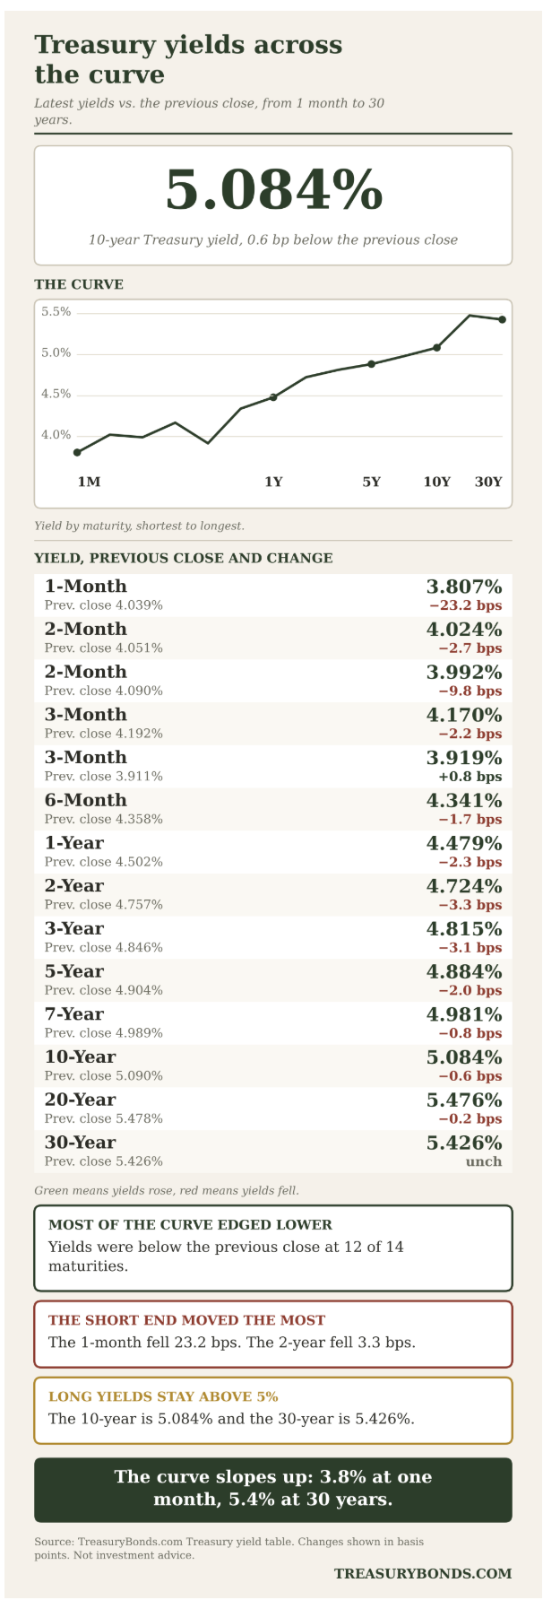
Treasuries started the day under pressure, bounced about an hour after the cash open and briefly turned positive in mid-morning trade. Then oil took over. Crude’s rally this week accelerated in the late morning on supply worries. Ukraine hit a refinery outside Moscow overnight, and there was intraday speculation that a pipeline in Saudi Arabia had also been attacked.
Plain language: higher oil means higher inflation risk, and that’s not what bonds want. Treasuries gave back their gains and returned to the morning lows.
Late in the day, some buying showed up as stocks kept struggling. That tilted the front end back into positive territory. The 10-year and 30-year didn’t make it, but they finished the week with solid gains.
The longer the maturity, the bigger the weekly drop in yield. That’s a good week for anyone holding longer bonds.
Oil and the dollar
Crude advanced nearly $10 a barrel this week and finished within $6 of its mid-September high of 106.75. The U.S. Dollar Index slipped 0.2% to 101.83, losing 0.4% for the week.
The data
Industrial production rose 0.7% in September, ahead of the 0.4% consensus. August was revised up to +0.1%. Production strengthened across manufacturing, mining and utilities, but capacity utilization stayed below its long-run average.
Import prices rose 1.1% in September, and 0.7% excluding oil. Export prices rose 2.2%, or 2.1% excluding agriculture. Prices are still moving up at the border.
Around the world
Eurozone CPI came in at 3.8% year over year, in line with expectations but up from 3.2%. Core was 2.5%.
Italy’s CPI hit 4.2% year over year, up from 3.3%.
Indonesia: MSCI said it’s looking at moving Indonesia from an emerging market to a standalone market, and the Jakarta Composite plunged 11%.
Japan is delaying formal adoption of a 3.5% defense spending target.
South Korea: September unemployment was 2.6%, and import prices were up 17.6% year over year.
What this week could mean for fixed income investors
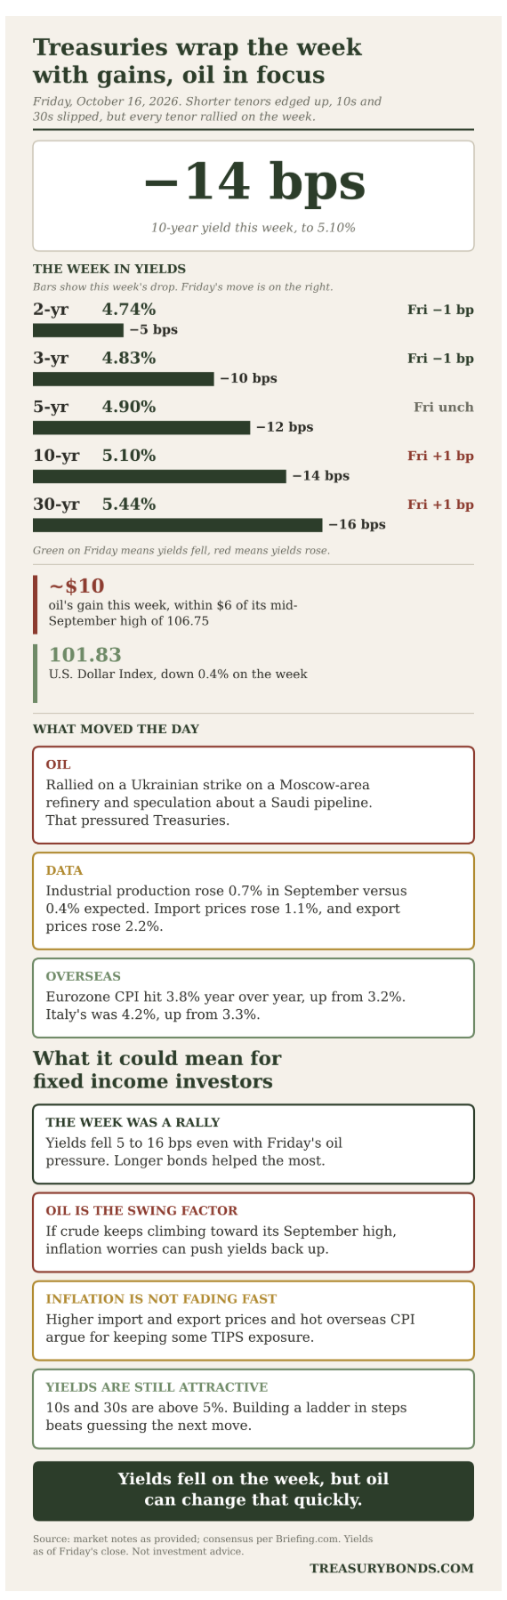
- Take the week’s win. Yields fell 5 to 16 bps even with Friday’s oil pressure. The 10-year is still above 5%.
- Watch oil. If crude keeps climbing toward the September high, inflation worries can push yields back up. It was the swing factor on Friday.
- Prices are still pushing. Hot import and export prices and rising CPI overseas argue for keeping some TIPS exposure.
- Keep building in steps. Yields above 5% in the 10s and 30s are attractive, and a ladder beats guessing the next move.
- Watch the dollar. A weaker dollar over the week is another sign markets are not worried about foreign demand for now.
Bottom line
Yields fell on the week, but oil can change that quickly.