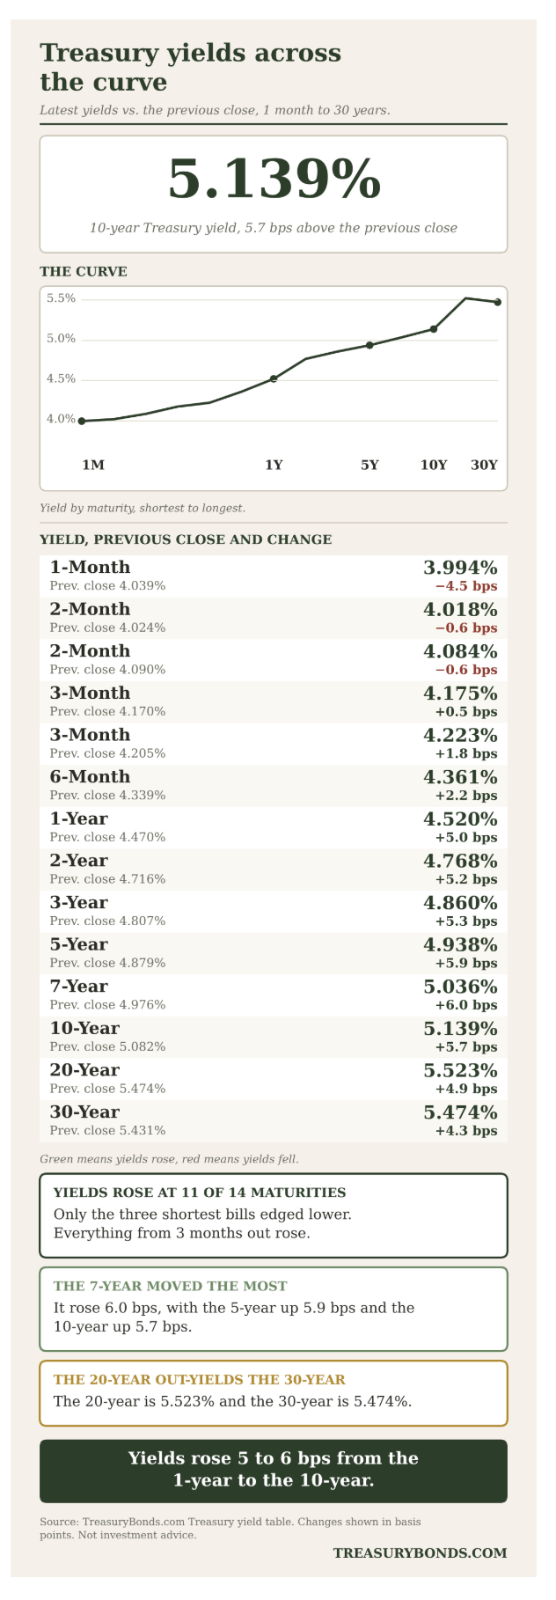
Treasuries started Monday in decent shape and then sold off all morning, finishing near the lows of the day. Yields rose across the curve, which gave back some of last week’s gains.
What happened
The open looked good. Overseas tech stocks rose overnight, which lifted sentiment, and oil briefly dipped below $100 a barrel on talk of another U.S.-Iran deal. Treasuries opened with small gains.
Then the deal talk faded. No follow-up reports came out, and oil rallied back toward its September high of $106.75. It was the eighth straight daily gain for crude. Treasuries sold off through the morning and stayed weak into the afternoon.
Putin offered a summit. He proposed a meeting with President Trump and China’s President Xi to find a way to end the war in Ukraine. That could take some pressure off global oil supply if it happens.
The long end took the worst of it. Yields on 10-years and shorter closed below Friday’s highs, but the 30-year ended about a basis point above its highest level from the last session. The U.S. Dollar Index rose 0.1% to 101.97.
Other news
Bank of America expects the FOMC to announce a 25-basis point hike this month.
Bank of Japan Governor said Japan’s underlying inflation is quite close to the 2.0% target.
Reserve Bank of Australia Governor Kent said there is evidence that neutral rates are rising in Australia and abroad.
China Q3 GDP came in at 1.2% quarter over quarter (expected 1.1%) and 4.5% year over year (expected 4.4%). September retail sales rose 1.1% year over year, well above the 0.5% expected. House prices fell 2.8% year over year, an improvement from -3.0% prior.
Japan: the August Tertiary Industry Activity Index fell to -4.10 from 0.70.
New Zealand: the September trade deficit was NZD1.971 billion, much wider than the NZD775 million expected.
U.K.: the Rightmove House Price Index rose 1.0% month over month.
What this could mean for fixed income investors
Oil is driving the tape. Crude up eight days in a row keeps inflation worries alive, and that keeps pressure on Treasury yields.
A Fed hike is a live possibility. If Bank of America is right, the short end of the curve has more to reprice.
The long end is the weak spot. The 30-year closed above Friday’s high yield, so it’s the part of the curve to watch.
Don’t chase a single day. A 4 basis point move doesn’t change a laddering plan. It does matter for what you pay on new purchases, since rates are 4.76% to 5.47% across the curve.
Headlines can reverse quickly. One day’s Iran or Ukraine talk moved oil by several dollars intraday, so be ready for yields to move both ways.
Bottom line
Treasuries sold off because oil rose and the Iran deal talk went nowhere. Yields are higher, the Fed could be hiking this month, and the long end looks the weakest.