The market is bracing for a big week with a Fed decision due Wednesday afternoon. Treasuries finished mixed, and for most of the day the market barely moved from where it started.
Shorter maturities finished weaker and the long end was slightly stronger.
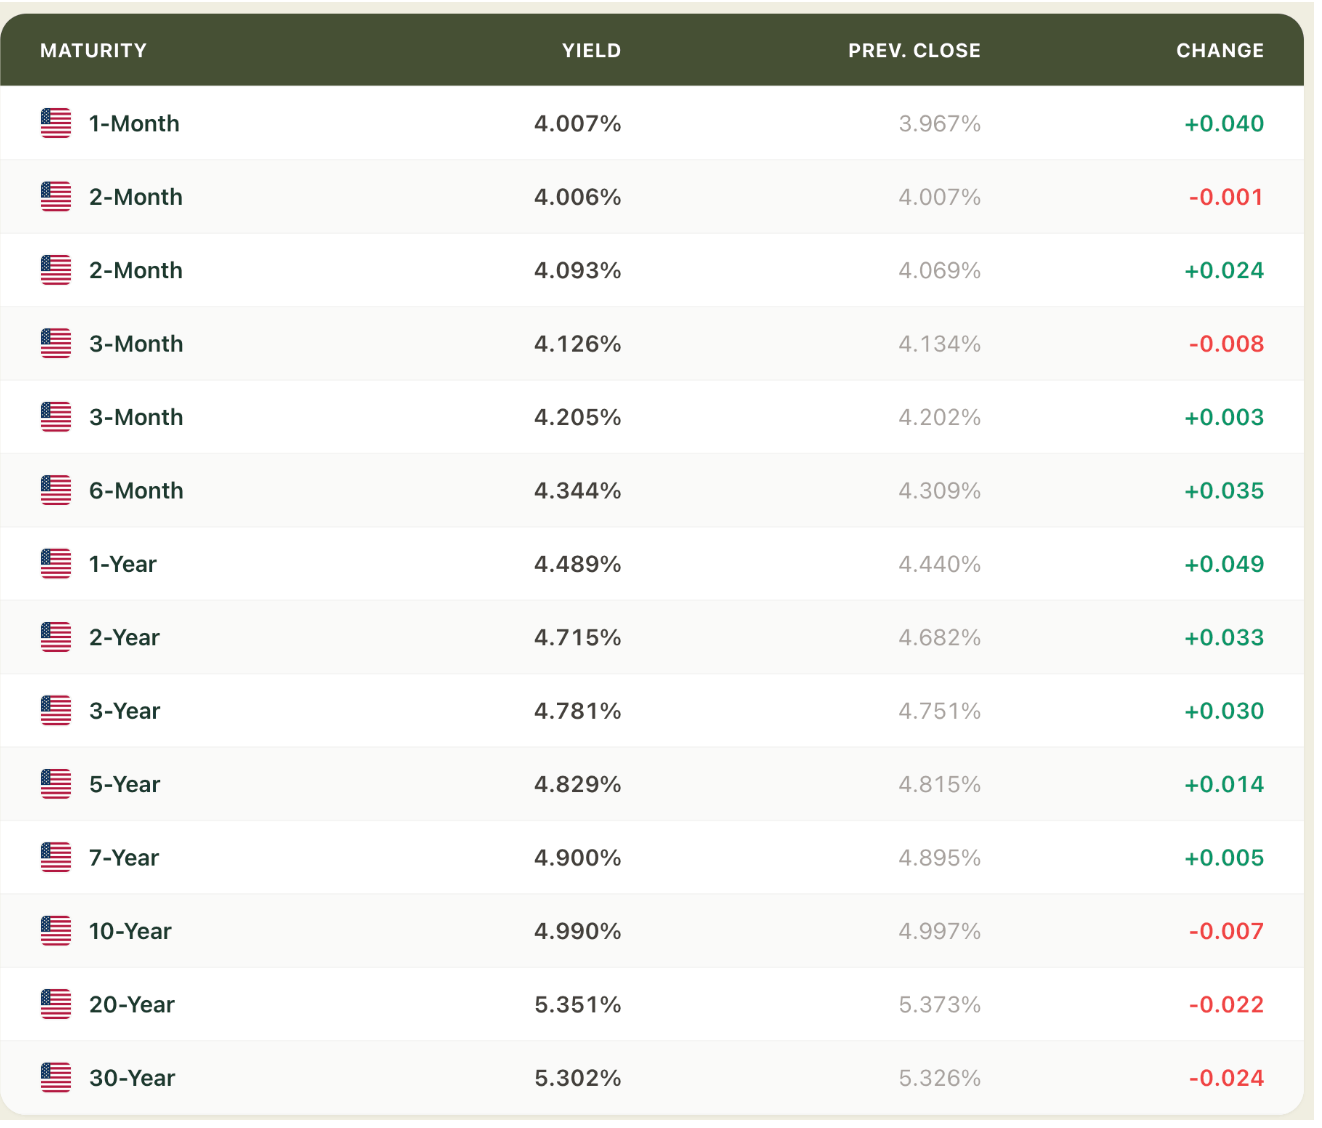
Shorter maturities underperformed from the start, following a night in which French government bonds extended Friday’s rebound. Moody’s didn’t downgrade France’s Aa3 rating on Friday, which eased some pressure there. Treasuries tried to bounce in the first couple of hours, helped by a lower oil price, but the rebound faded and prices drifted back to their opening levels.
The 2-year auction was soft
In the early afternoon, the Treasury kicked off this week’s auctions with a $69 billion 2-year note sale. Demand was weak, and the front end felt some light pressure. The long end barely reacted.
Compared with the average of the last 12 auctions:
High yield: 4.708% (average 3.942%)
Bid-to-cover: 2.59 (average 2.62)
Indirect bid: 45.7% (average 58.7%)
Direct bid: 41.3% (average 28.9%)
The takeaway is that the usual big buyers, the indirect bidders, showed up less than normal, while direct bidders showed up more.
Oil and the dollar
Crude slipped below $102 a barrel, even with ongoing speculation about possible military action against Iran. The U.S. Dollar Index rose 0.1% to 101.93.
Economic data from overseas
Japan, August: Coincident Indicator -1.8% m/m (expected -1.9%; prior +1.7%). Leading Index +0.4% m/m (expected +0.4%; prior +1.5%), and the index level was 118.0 (expected 118.0; prior 117.7).
Singapore, September industrial production: +3.4% yr/yr (prior +15.4%) and -3.9% m/m (prior -1.0%).
Germany, October Ifo: Business Climate 90.2 (expected 90.0; prior 89.9). Expectations 91.6 (expected 90.0; prior 90.4). Current Assessment 88.8 (expected 89.9; prior 89.5).
Spain, September PPI: +18.3% yr/yr (prior +13.2%).
U.K., October CBI Distributive Trades: -10 (expected -47; prior -55).
What’s ahead
Tuesday: a $70 billion 5-year note auction.
Wednesday: the October FOMC statement in the afternoon, with no auction that day to make room for it.
Bottom line
Not much changed on Monday, but the market is clearly waiting. Shorter yields edged higher after a soft 2-year auction, the long end held steady, and the real tests come Tuesday with the 5-year sale and Wednesday with the Fed.