Treasuries spent a third straight day in a tight range, and the market is clearly waiting on tomorrow’s FOMC statement.
Prices ended with slim losses. The day started on a firmer note, with oil under pressure overnight and hints of diplomatic progress toward ending the war in Ukraine. That didn’t last. Once September durable goods orders came in above expectations, the market turned negative. The selling faded quickly, though, and the 10-year note returned to its 50-day moving average (4.995%).
Here’s the yield check:
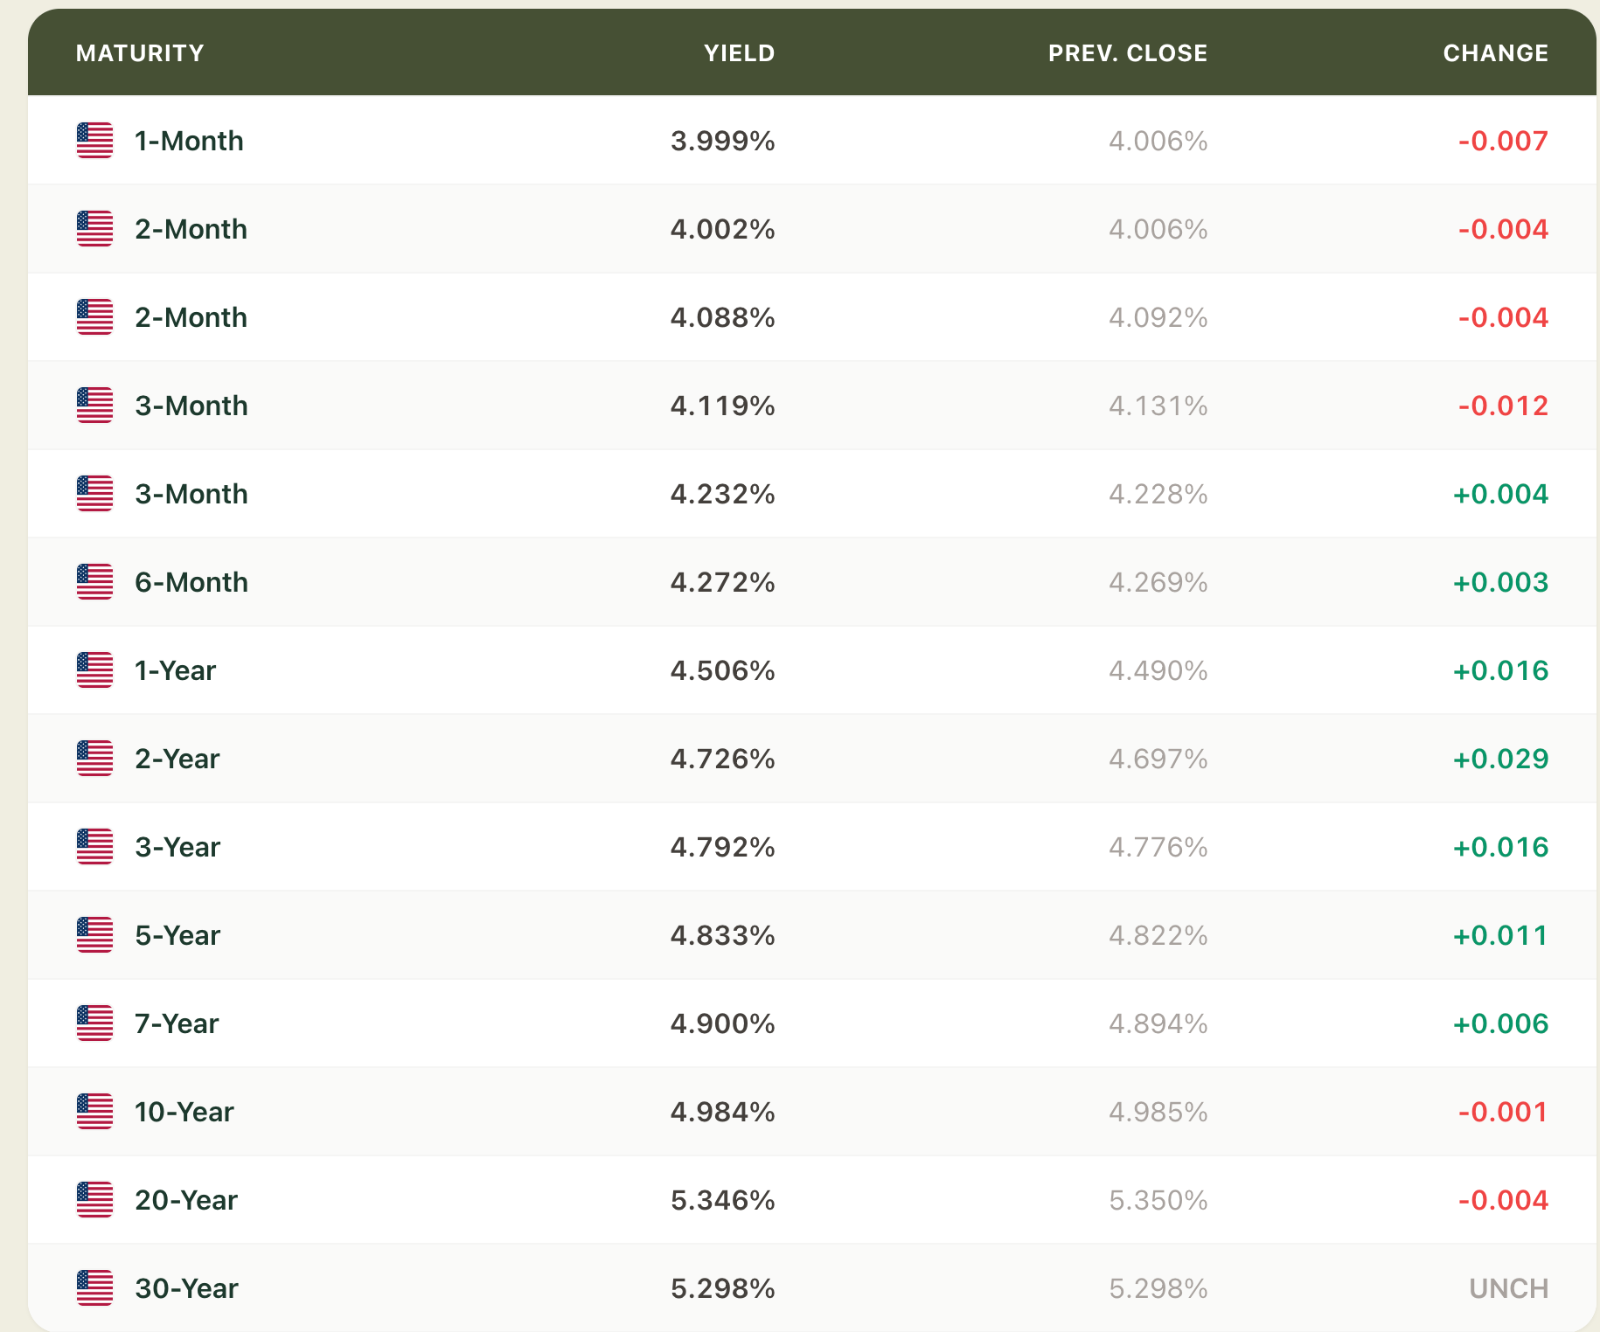
Shorter maturities underperformed slightly but stayed above their morning lows.
Another weak auction
Today’s $70 billion 5-year note sale met weak demand, following yesterday’s underwhelming 2-year auction.
Oil and the dollar
Crude slipped below $100 a barrel. The U.S. Dollar Index rose 0.4% to 102.31.
Today’s data
Durable goods: Orders rose 1.8% in September versus a 1.0% consensus, after an upwardly revised 0.1% in August. Excluding transportation, orders rose 0.5% (consensus 0.6%). The key takeaway is ongoing strength in business spending: new orders for nondefense capital goods excluding aircraft rose 0.5%, after 1.6% in August and 0.6% in July.
New home sales: Down 0.6% to 676,000 (consensus 655,000), from a downwardly revised 680,000. They’re down 5.3% from a year ago. Sales stalled despite a lower median price, with rising mortgage rates limiting affordability.
Consumer confidence: The Conference Board index rose to 91.7 in October (consensus 80.5) from an upwardly revised 84.2. A year ago it was 95.5. Both the present situation and expectations improved, helped by easing gas prices.
Home prices: The FHFA index rose 0.3% in August (consensus 0.2%). The S&P Case-Shiller index was up 2.7% year over year (consensus 2.8%), up from 2.5% in July.
The news
Ukraine: Norway’s prime minister and Finland’s president spoke with Vladimir Putin about ending the war, calling the discussion “frank and substantive.”
Tariffs: The U.S. and Canada are working to reduce Section 232 tariffs on steel and vehicles.
Japan: Former Bank of Japan Governor Kuroda spoke in favor of additional rate hikes. BoJ core CPI rose 2.5% year over year (prior 2.3%), and the corporate services price index rose 3.7% (expected 3.7%; prior 3.5%).
New Zealand: The central bank is expected to raise its cash rate to 3.00% from 2.75% overnight.
Europe: The ECB’s quarterly lending survey showed further tightening of credit standards for loans to firms. France’s October consumer confidence was 80 (expected 85; prior 85). Spain’s Q3 unemployment rate was 10.18% (expected 9.90%; prior 9.87%). Eurozone September M3 money supply rose 3.5% year over year, in line with expectations, and private sector loans rose 3.1%.
Brazil: Flavio Bolsonaro, ordered to surrender his passport after losing Sunday’s election, has reportedly fled to the U.S., according to Reuters.
Israel: Turnout appears to be a record in today’s election, which could unseat Prime Minister Netanyahu.
South Korea: Q3 GDP rose 1.0% quarter over quarter (expected 0.7%; prior 0.6%) and 3.4% year over year (expected 3.0%; prior 3.7%). October consumer confidence was 105.4 (prior 106.6).
China: Industrial profits rose 15.5% year to date through September (prior 15.7%).
Bottom line
Not much moved today, but the data leaned toward a resilient economy, and demand for Treasuries at auction was lukewarm.