Treasuries finished Wednesday in a mixed mood. The Fed held rates as expected, but the statement leaned tougher, and the longer end of the curve felt it.
The 2-year ended unchanged, while the 10-year and 30-year closed higher. Oil near $103 a barrel kept adding to the pressure all day.
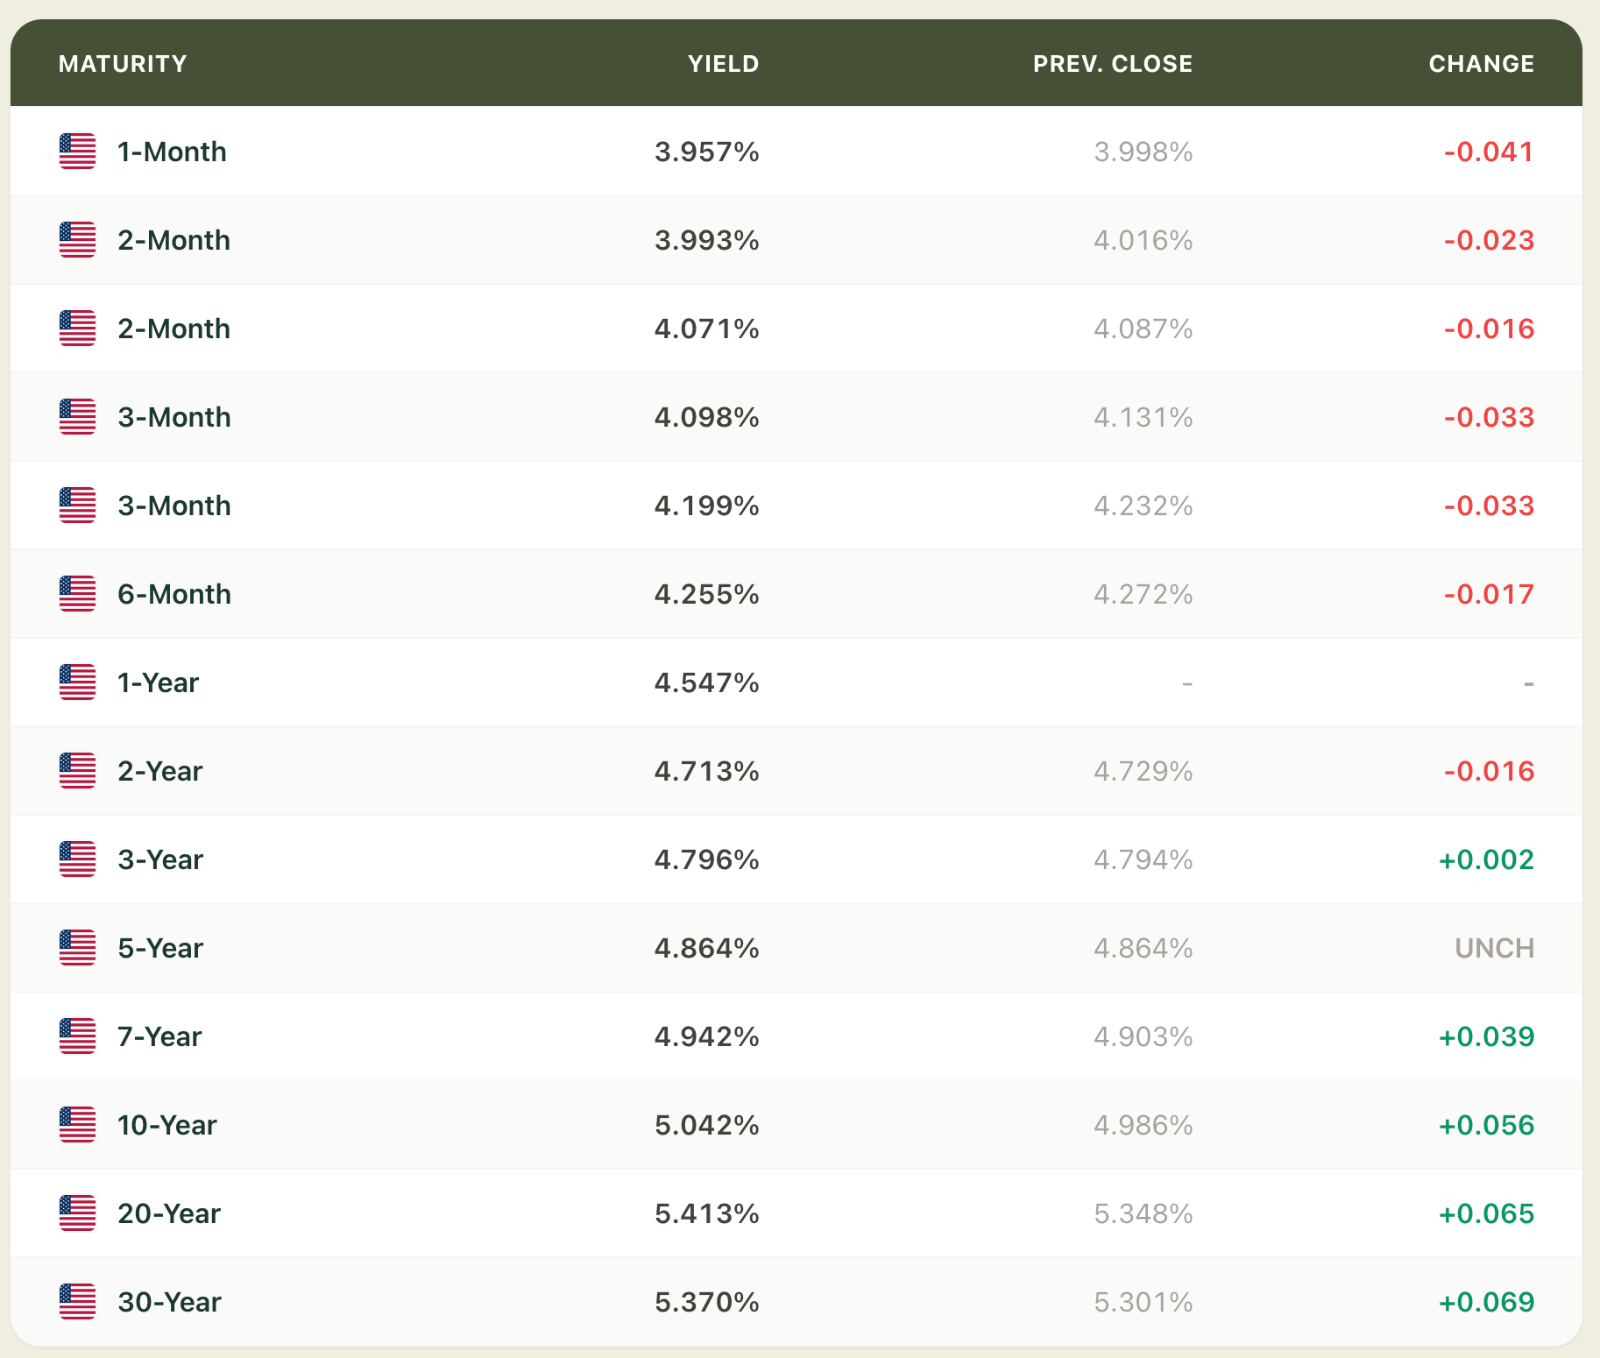
The 10-year is back above its 50-day moving average (5.002%), while the 30-year sits three basis points below its own (5.390%).
What the Fed did, and said
As expected, the Fed held at 3.75% to 4.00%. But two members dissented in favor of a hike. The statement said economic activity is growing at a strong pace, spending is resilient, capital investment is robust and unemployment has changed little. It also repeated that inflation remains elevated. Some read that as laying the groundwork for a rate hike in December.
Chairman Warsh offered a bit of a counterpoint. He pointed to this month’s pullback in market rates as a sign that inflation expectations have stepped back from their peak. In other words, the Fed sees some of the tightening already being done by the market.
Oil and the dollar
Crude revisited this week’s high and settled just under $103 a barrel. Higher oil feeds inflation worries and was a big reason yields rose earlier in the day. The U.S. Dollar Index gave back most of yesterday’s gain, down 0.2% to 102.13. Weekly crude inventories fell by 1.892 million barrels after a 3.06-million-barrel drop the week before.
Around the world
Bank of Canada: raised its policy rate by 25 bps to 2.50%, as expected, and sees 3.1% inflation in 2027.
Reserve Bank of New Zealand: held at 2.75%, though markets expected a 25-bp hike.
Australia: RBA Governor Bullock said the labor market is a bit tighter than thought and acknowledged persistent inflation pressure, which led to some selling in Australian debt. Q3 CPI was +1.3% q/q and +3.9% y/y, in line with expectations. Trimmed mean was +3.7% y/y (expected +3.6%), and the September monthly indicator was +4.3% y/y (expected +4.2%).
ECB: announces its policy tomorrow morning. No change to the interest rate corridor is expected.
Germany: November GfK Consumer Climate was -30.8 (expected -30.1).
Italy: September PPI rose 2.9% m/m and 13.8% y/y (prior 10.9%). August industrial sales fell 0.9% m/m.
Switzerland: October ZEW Expectations were -15.3 (prior 2.6).
U.S. data
MBA Mortgage Index: up 3.4% after last week’s 5.3% drop. Purchases +3.8%, refinancing +2.7%.
Advance goods trade deficit: widened to $134.9 billion in September (consensus $128.7 billion) from $132.1 billion in August.
Advance wholesale inventories: +0.5% in September (as expected), after +0.7%.
Advance retail inventories: +0.3% after +0.3%.
Bottom line
Strong growth, elevated inflation and two dissenters pushing for a hike left long yields higher and the short end flat. With oil above $100 and talk of a possible December hike, the bond market has plenty to chew on.