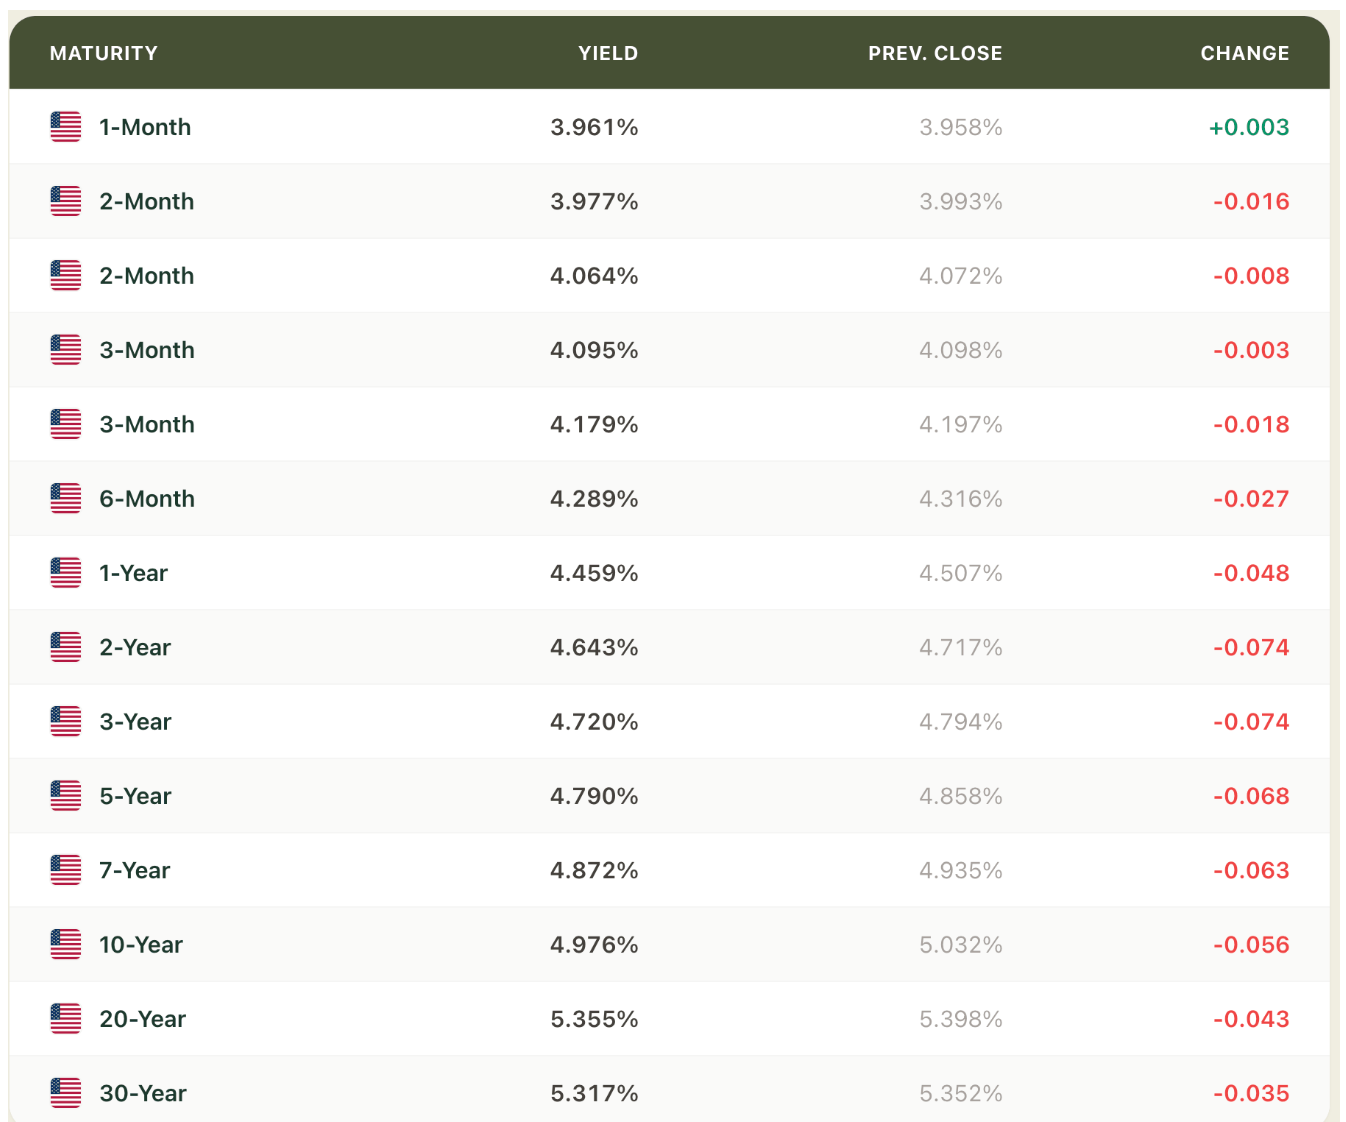
After a bumpy session on Wednesday following the Fed, yields fell across the curve, helped by a cooler read on inflation inside a strong GDP report.
The 10-year ended back below its 50-day moving average, and the odds of a December rate hike slipped.
The big story: strong growth, cooler inflation
The advance reading of Q3 GDP came in at 3.4%, ahead of the 3.0% expected, led by consumer spending, investment and government spending.
Core PCE slowed to 2.5% from 3.3% in Q2, the lowest since Q3 2024.
The GDP price index rose 2.2%, well under the 3.5% expected and a big drop from 6.1% in the second quarter.
That led to some early talk of a more patient Fed, especially after Chairman Warsh said yesterday that this month’s pullback in market rates is a sign inflation expectations have stepped back from their peak.
The Fed bet
The market still expects a 25-basis-point hike in December, but the implied probability slipped to about 78% from 85% yesterday.
The ECB and the auction
Treasuries extended gains after the European Central Bank acknowledged that financing conditions have tightened since its last meeting and that this is likely to weigh on inflation and growth.
That got traders thinking the ECB’s tightening could be closer to an end.
Much of the post-ECB bid faded over the next couple of hours, and Treasuries traded sideways through the afternoon.
The Treasury finished the week’s auction slate with a decent $44 billion 7-year note sale:
High yield: 4.894% (12-auction average 4.197%)
Bid-to-cover: 2.46 (2.48)
Indirect bidders: 57.8% (63.0%)
Direct bidders: 32.8% (25.3%)
Indirect demand was a bit lighter than average and direct demand was heavier. The week’s auctions overall were described as mediocre.
Other U.S. data
Initial jobless claims: 194,000 (196,000 expected), down 1,000. Still historically low.
Continuing claims: 1.701 million, down 21,000.
Natural gas inventories: up 80 bcf, after a 77 bcf increase last week.
Atlanta Fed GDPNow for Q4: starts at 3.2%.
Oil: just above $102 a barrel, after an overnight dip.
Dollar Index: down 0.2% to 102.02.
Around the world
ECB: Lagarde will step down on February 7, with speculation she will be named to chair the World Economic Forum.
New Zealand: The central bank governor said there’s a high chance of a rate hike in December. October business confidence was 52.5.
Hong Kong: The HKMA left its policy rate at 4.25%, following the Fed.
U.K.: The autumn budget cut planned long-term gilt issuance in favor of short-term bills. Mortgage approvals (53.44K) and lending came in below expectations.
Italy: Approved a EUR26 billion budget for 2027. Consumer confidence fell to 90.3 (90.9 expected).
Eurozone: The October business and consumer survey was 96.9 (97.5 expected). Services sentiment was 5.3 (5.9 expected).
Spain: September retail sales fell 1.4% year over year.
Japan: October household confidence was 35.0 (35.1 expected). Foreign investors bought JPY1,180.9 billion of Japanese stocks and sold JPY92.6 billion of bonds.
Australia: Q3 import prices fell 1.1% q/q (a 1.3% rise was expected).
South Korea: October Manufacturing BSI at 78 (79 prior).
A good day for Treasuries, with strong growth and cooling inflation giving the market a reason to trim the odds of a December hike. Year-over-year inflation is still well above target, oil is above $100, and the labor market is tight.