The AI buildout is expensive.
Alphabet’s Class A shares fell 12.6%, this was the biggest one-day drop since the 2004 listing.
The reason wasn’t weak demand.
It was how much cash the company is burning, and how it’s paying for it.
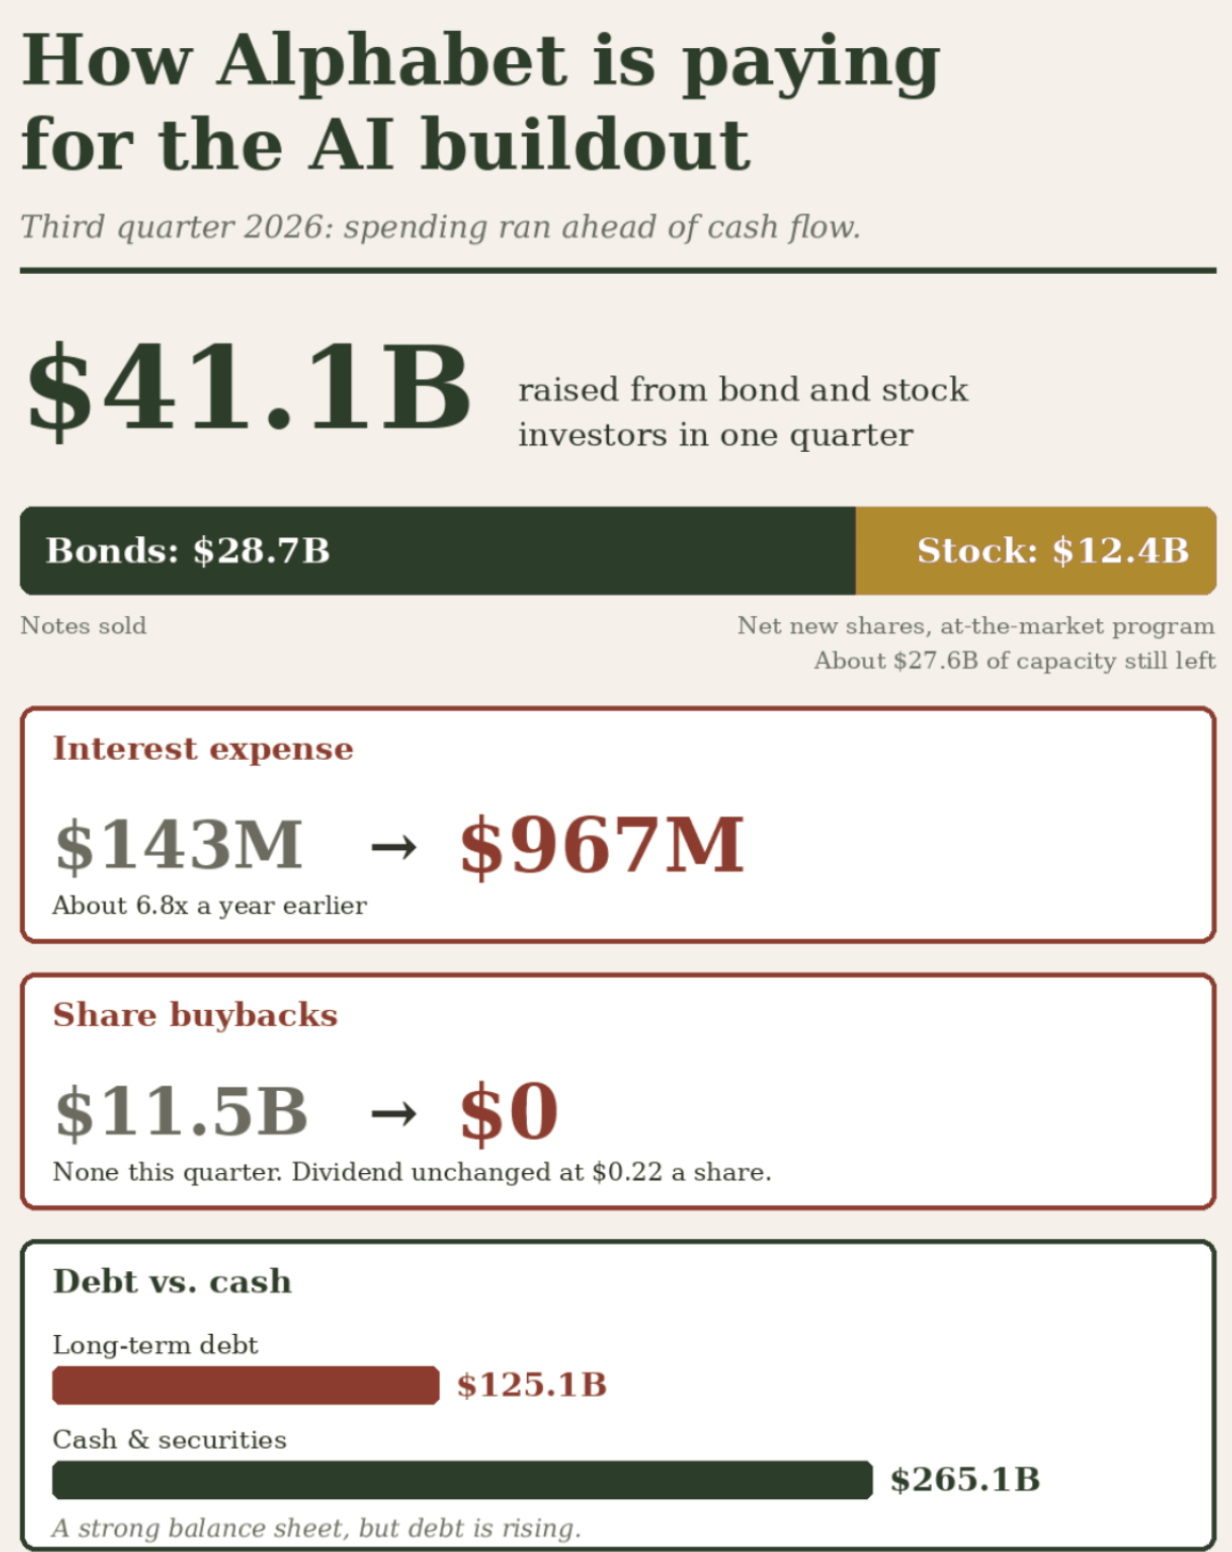
Alphabet has been in the bond market often this year: a global multi-tranche deal in February, euro, yen and Canadian-dollar offerings in May, and a U.S. sale of up to $25 billion in August.
Selling both bonds and stock in the same quarter is what rattled investors: it signals that even one of the richest companies in the world needs outside money to keep up.
Alphabet’s business is not weak. It’s that the business is growing fast while spending even faster.
Hyperscaler debt is a big new supply. Alphabet is just one of several giants issuing heavily to fund AI, and investors have to absorb it.
With $265 billion in cash and securities, Alphabet’s credit looks solid. But long-term debt of $125 billion and interest expense up more than six times are changes worth watching.
Several of the largest investment-grade issuers are now tied to the same AI theme.
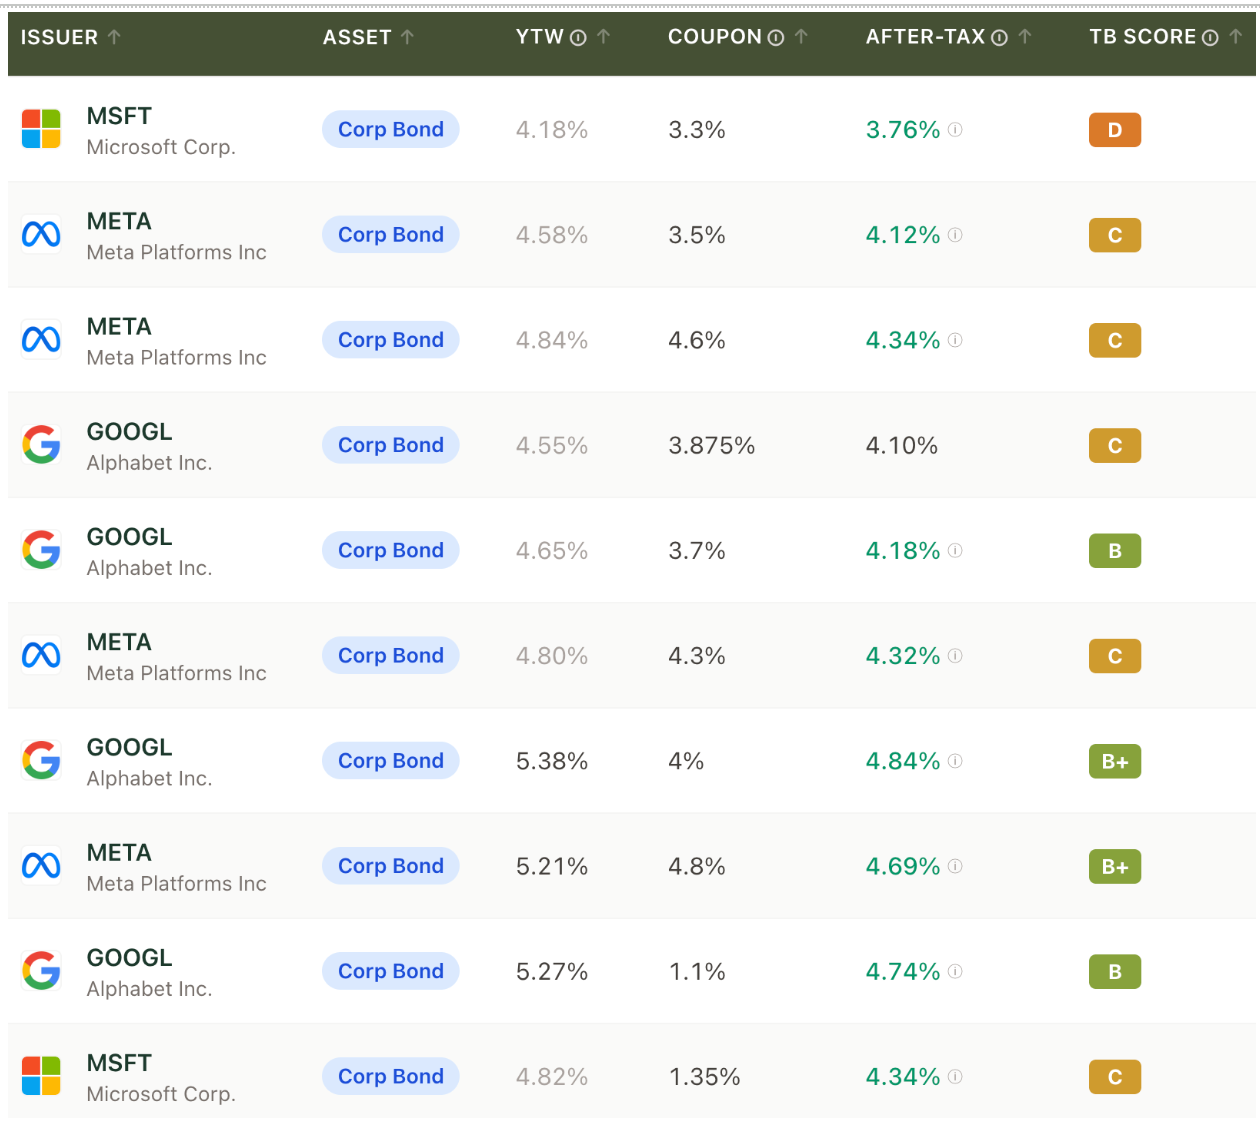
Bottom line: Diversify your corporate exposure.