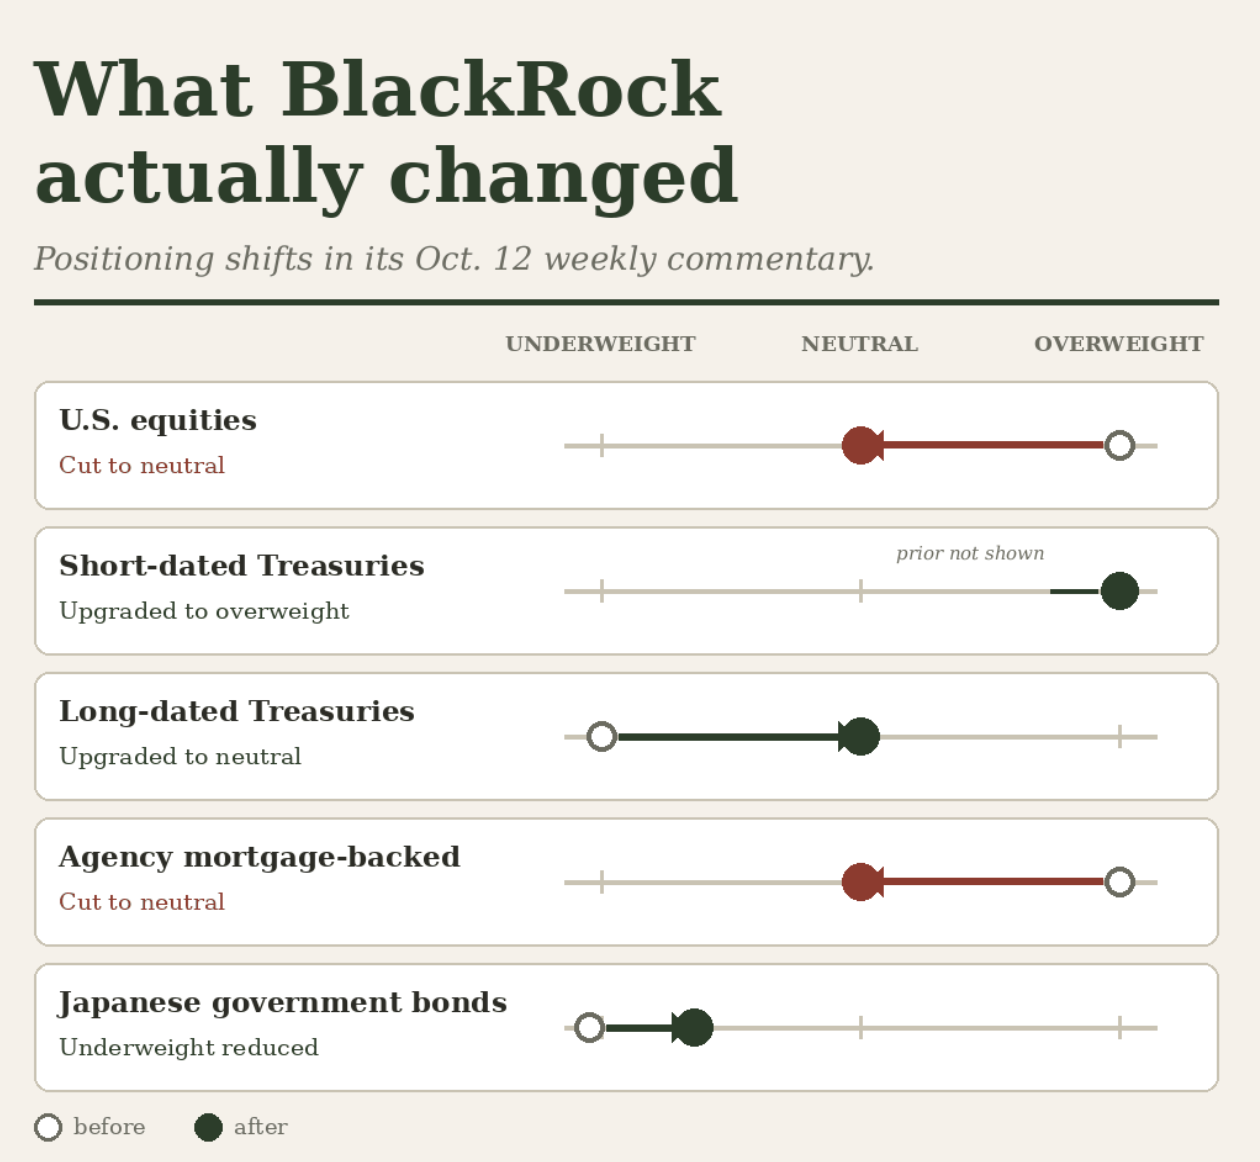
For most of the past six years, BlackRock was underweight long-dated Treasuries.
It first took that stance in October 2020, when the 10-year yield was near 0.9%. The firm moved short-term Treasuries to overweight, bumped long-dated Treasuries up to neutral and cut its U.S. equity overweight to neutral.
The timing seems right.
The 10-year Treasury yield is up about 110 basis points this year, to around 5.25% when BlackRock published, after briefly topping 5.3%, a multi-decade high.
The increase is driven mainly by higher real rates, meaning yields after inflation, not just inflation worries.
Compared with 2020, a big chunk of today’s yield is real return, and the estimated term premium, which was negative for much of the last several years, is back in positive territory.
Stocks and bonds are competing again.
With real yields at the highest since about 2007, the risk-reward between the two has changed.
Check out your portfolio and see if changes should be contemplated.