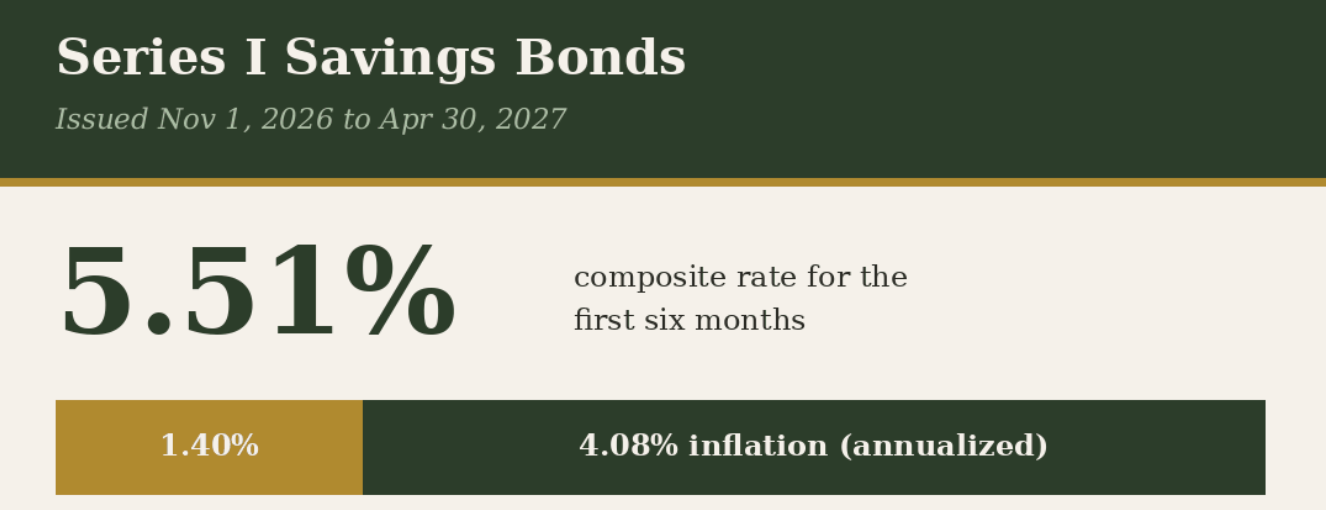
Treasury just announced the new rate for Series I savings bonds. For bonds issued from November 1, 2026 to April 30, 2027, the composite rate is 5.51%, up from 4.26%. It includes a 1.40% fixed rate, up from 0.90%.
How the rate works
The 5.51% has two pieces.
The fixed rate, 1.40%, stays with the bond for its entire life.
The inflation piece is reset every six months based on CPI.
Right now it works out to about 4.08% annualized (2.04% over six months), up from about 3.34%.
Your rate for the first six months is 5.51%. After that, the inflation piece changes, and the fixed 1.40% stays.
The pros
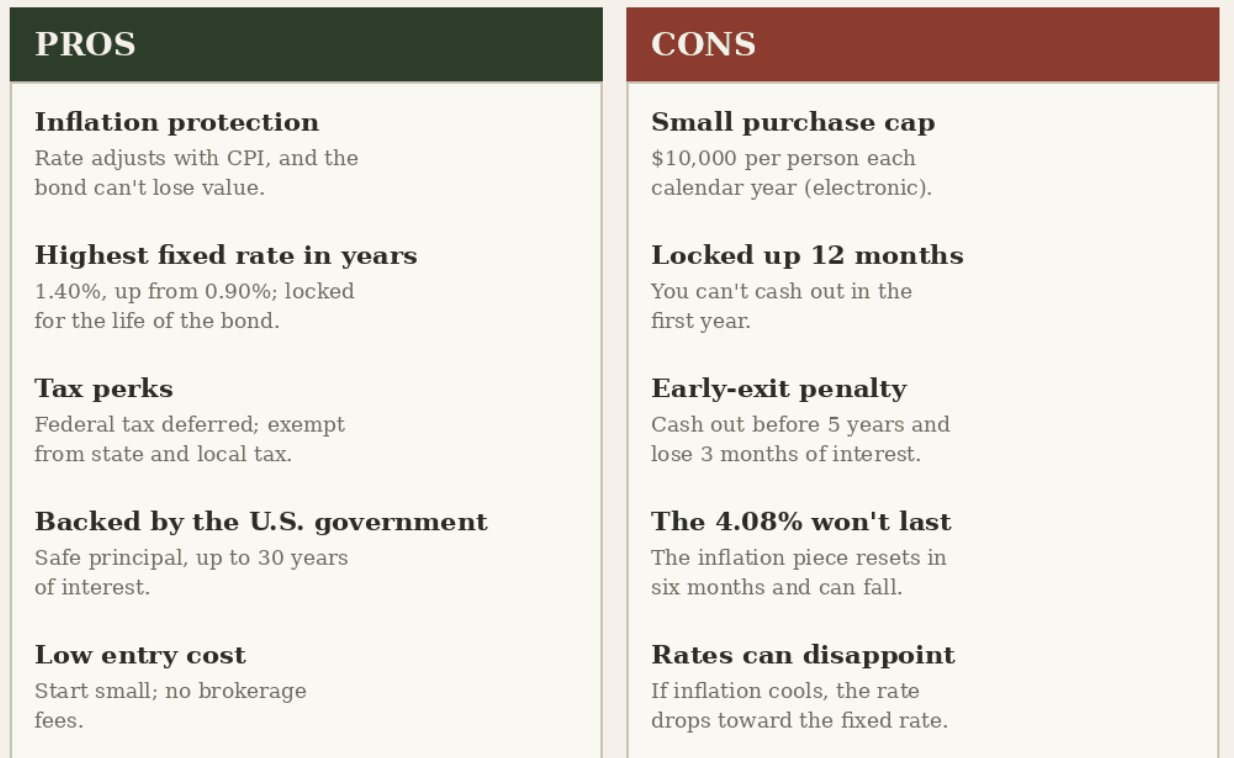
Inflation protection. Your rate moves with CPI, and an I bond can’t lose value.
A higher locked-in fixed rate. 1.40% above inflation for life is a big improvement on 0.90%.
Tax perks. Interest is exempt from state and local income tax and you can defer federal tax until you cash out or the bond matures.
Government-backed. Safe principal, earning interest for up to 30 years.
Easy to start. No brokerage account needed, just TreasuryDirect.
The cons
The purchase cap. You can buy only $10,000 per person per calendar year electronically.
A 12-month lockup. You can’t cash out in the first year.
An early-exit penalty. Cash out before five years and you lose the last three months of interest.
The 4.08% won’t last. It resets in six months and can fall if inflation cools.
A 1.40% fixed rate plus inflation protection, tax deferral and government backing is a strong package for a small, safe slice of your savings. If you can lock up $10,000 for at least five years, it’s worth a look. If you need flexibility or want to put more to work, TIPS and Treasuries deserve a look too.