Everyone loves stocks when they’re going up. Nobody loves bonds in a bull market, and that’s usually when someone asks, “Why bother with the 40%?".
A recent comparison answers it well. It looked at an annually rebalanced 60/40 portfolio against 100% equities over 21 complete calendar years, 2004 through 2024.
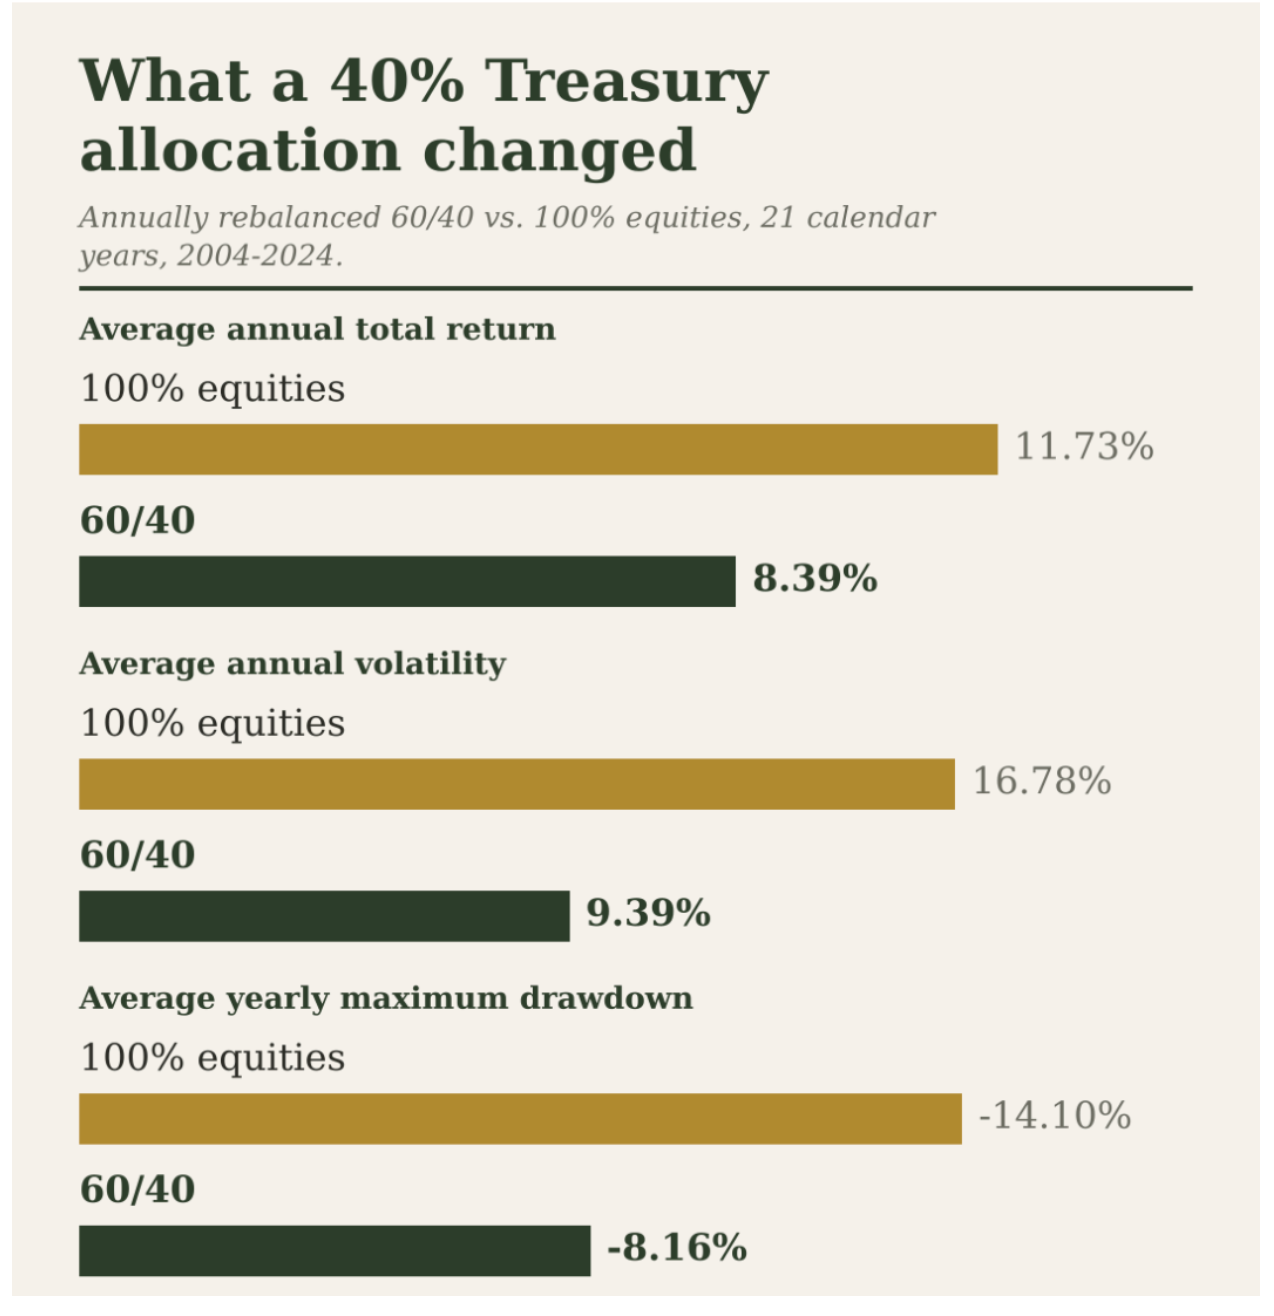
Stocks earned more (as we all expected).
That’s not in dispute. But the 60/40 delivered about three-quarters of the return with a much smoother ride, and for most people that’s the difference between sticking with a plan and abandoning it.
The point of the 40% isn’t to beat stocks.
It’s to help you stay invested long enough for the 60% to do its job.
Returns on paper and returns in real life are different.
The investor who earns 11.73% on average but panics and sells during a 30% drop doesn’t get 11.73%.
The investor who holds a smaller drawdown may be far more likely to stay put.
Most people don’t blow up their portfolios by picking the wrong asset.
They blow them up by selling at the wrong time.
A smaller drop makes that mistake less likely.
It also matters when you’re drawing money. Someone taking withdrawals in retirement doesn’t want to sell stocks at the bottom to pay bills. The Treasury sleeve is the one place to take cash from without selling stocks at a low.