Treasuries gave back some of Monday’s gains on Election Day, and the long end took most of the hit.
After outperforming yesterday, the 10- and 30-year led yields higher, while the market spent the afternoon back near Friday’s lows.
Oil set the tone
The session opened lower after limited overnight U.S. strikes on targets in Iran pushed oil up. Crude pulled back from its high in the morning and briefly dipped below its 50-day moving average (95.04).
That coincided with an attempt to bounce in Treasuries, but the rebound faded when oil climbed back above the average.
A couple more hours of selling brought yields back to Friday’s levels, where the market stayed.
Crude settled just above $96 a barrel, and the U.S. Dollar Index rose 0.1% to 101.88.
Economic data
Factory orders rose 1.8% in September, ahead of the 1.2% consensus, after an upwardly revised 0.3% gain in August.
Excluding transportation, orders rose 1.3%, and shipments of manufactured goods jumped 1.3%.
The report showed broad-based strength, with gains in transportation equipment, primary metals, fabricated metals, machinery, and computers and electronics.
Job openings rose to 7.523 million in September from a revised 7.190 million, well above the 7.100 million consensus. I
t’s the first rise in five months, and it adds a positive signal about the labor market.
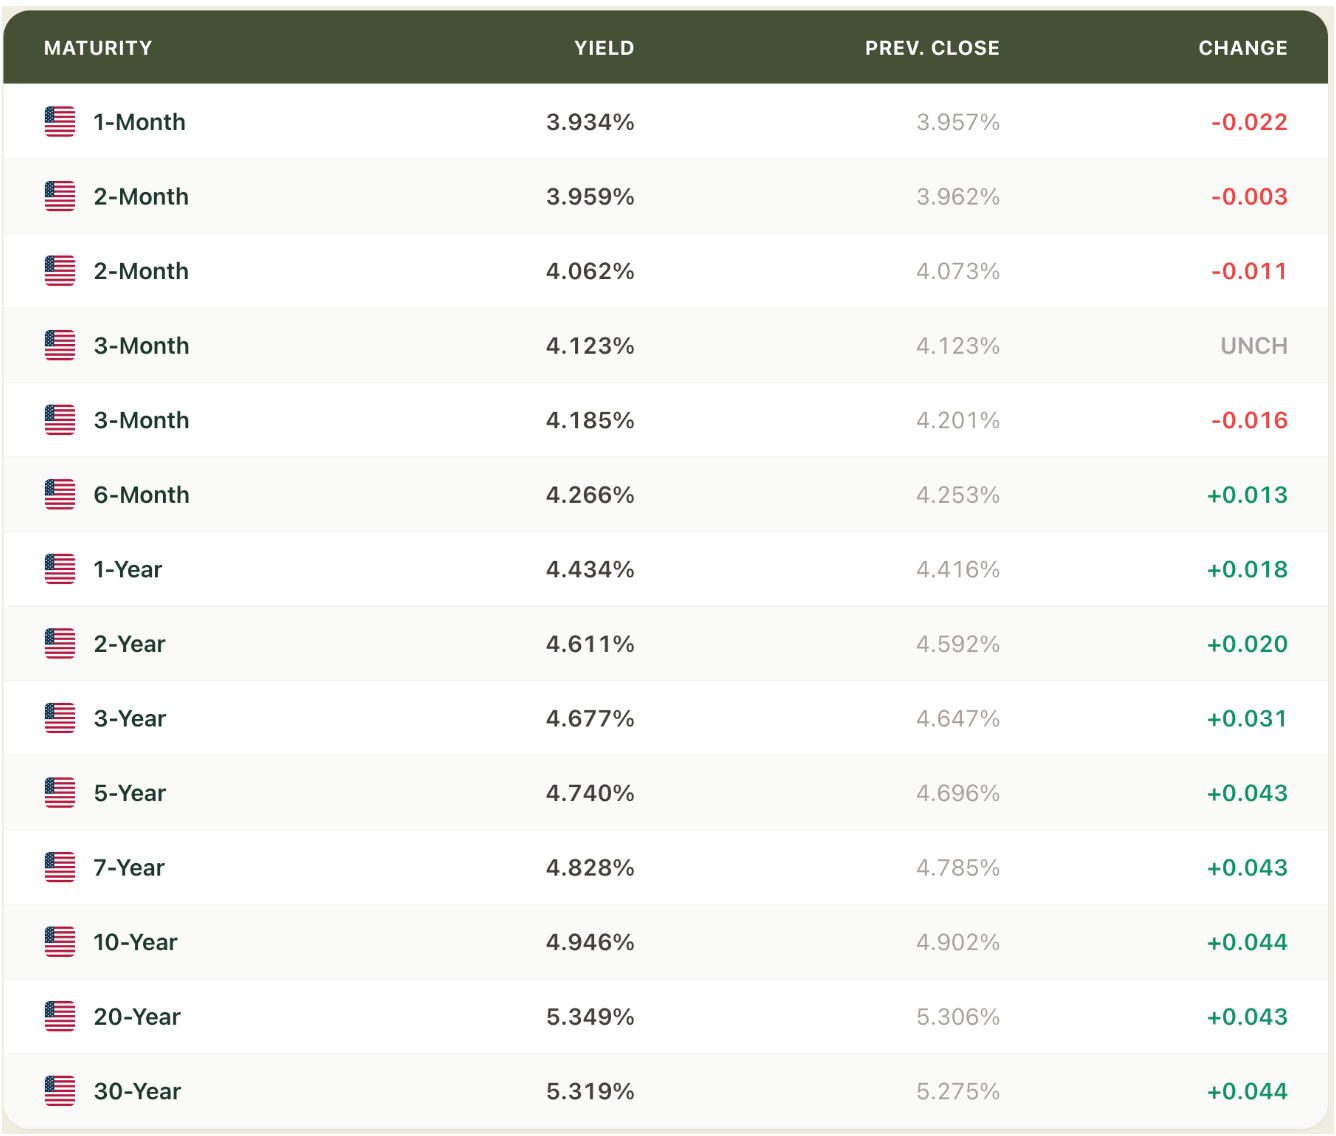
The yield check
Around the world
The Reserve Bank of Australia raised its cash rate by 25 basis points to 4.85%, though three policymakers voted for no change.
In China, the National Development and Reform Commission pledged extraordinary support for key technology breakthroughs, and the People’s Bank of China cut its stock buyback relending rate by 25 basis points to 1.00%.
Switzerland’s October CPI came in hotter than expected at 1.5% year over year (consensus 1.3%), while South Korea’s CPI slowed to 2.8%.
Hong Kong’s third-quarter GDP rebounded to 1.9% quarter over quarter.
On the geopolitical front, the U.S. will mediate a meeting between leaders from Russia and Ukraine in Abu Dhabi next Tuesday and Wednesday.
President Trump also said a deal has been reached to discontinue military aid payments to Israel at the end of this year.
What’s coming tomorrow
The calendar is busy.
At 8:15 ET, the October ADP report (consensus 75,000, prior 90,000).
At 8:30 ET, the September trade balance (consensus -$108.4 billion) and the Treasury’s quarterly refunding announcement, which will tell us how much more debt is coming and in what sizes.
At 9:45 ET, the final October services PMI, followed at 10:00 ET by the ISM Non-Manufacturing Index (consensus 54.8, prior 54.9) and at 10:30 ET by weekly crude inventories.
The refunding is the one everyone's watching, given how much attention the long end has been getting.