Thursday was a flight-to-safety day. Stocks stumbled again on AI worries, the Nasdaq slipped below its 200-day moving average and the S&P 500 flirted with its own.
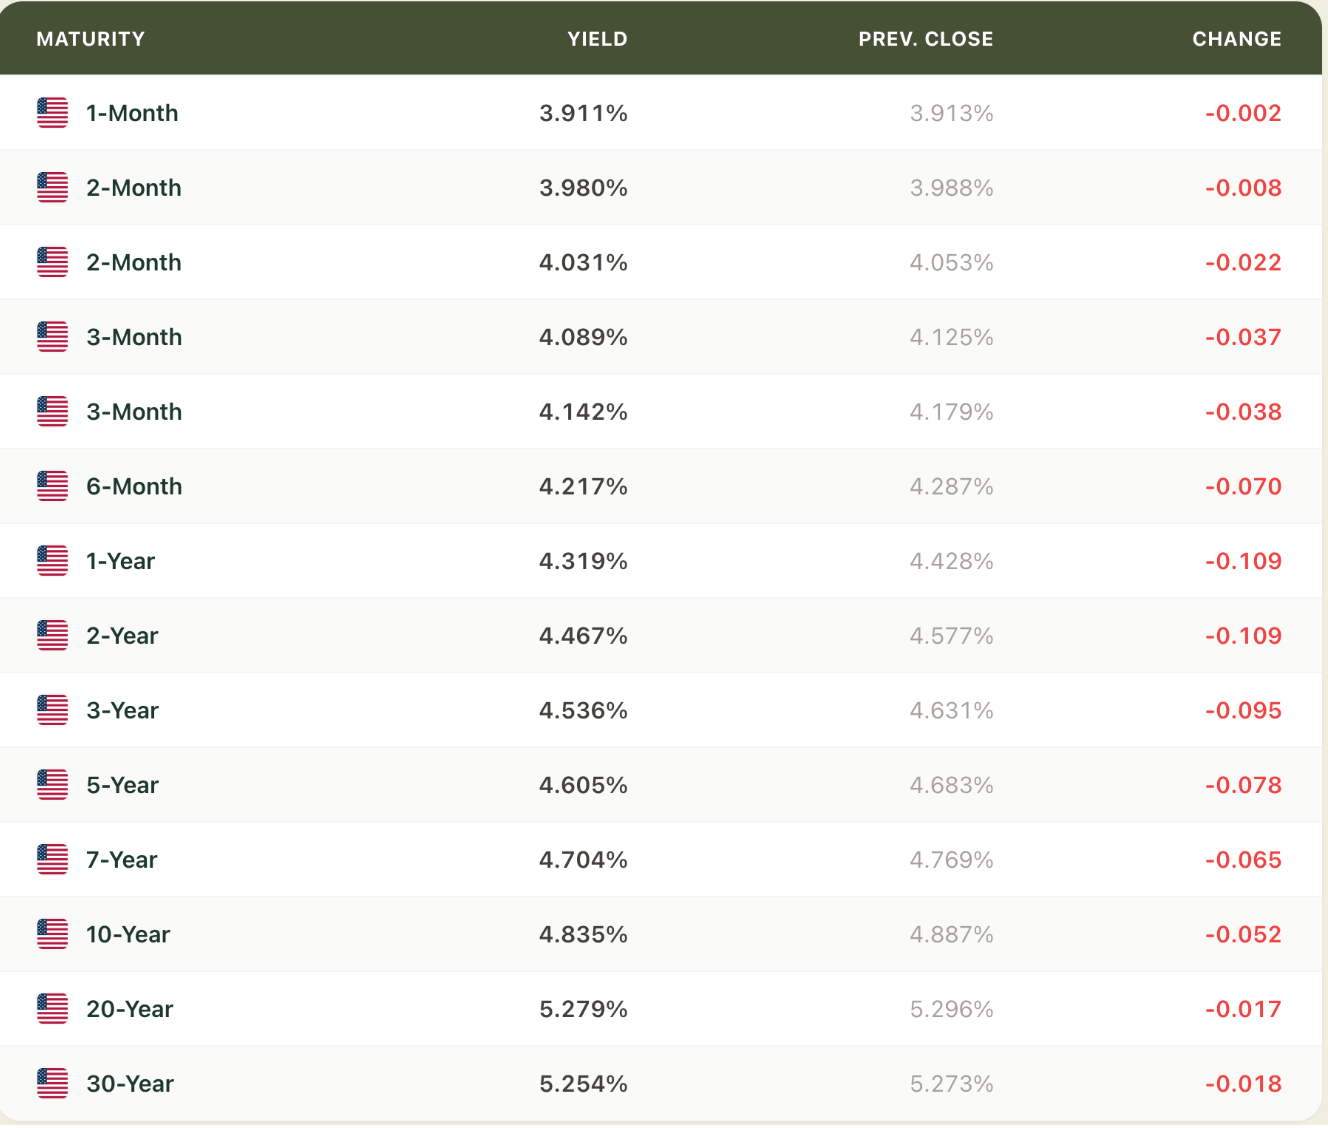
Treasuries were the place to hide, and yields finished at their lowest levels since the second week of September.
A strong economy underneath
Jobless claims: Initial claims fell to 189,000, the lowest since July and below the 197,000 forecast. Continuing claims rose 23,000 to 1.718 million. There’s little layoff activity.
Productivity: Q3 productivity grew 3.6%, above the 3.1% forecast, and unit labor costs fell 0.7% against an expected 1.4% rise. Faster output with lower labor costs is good for corporate profits and takes some pressure off inflation.
Other markets
Gold: It rose 1% to $4,112.90 and is up more than $200 this week.
Crude: WTI gained 2.6% to $90.55, bouncing off its 200-day moving average.
Copper: It fell 2.5% to $6.27.
Dollar: The Dollar Index sits near 101.55, with USD/JPY down 0.4% to 157.81.
Rates abroad
Bank of England: It raised rates 25 bps to 4.00% by an 8-1 vote and projects CPI near 5% by mid-2027.
Bank of Japan: September minutes showed members agree more hikes are needed.
Fed: Richmond Fed President Barkin, a 2027 voter, expects gradual rate hikes.
Europe: Eurozone PPI rose 11.1% year over year, and construction PMIs in the euro area, Germany, France and the U.K. all showed contraction.
Apple taps the bond market
Apple sold about $7 billion of investment-grade debt in seven tranches. The deal drew $31 billion in orders, about 4.4 times the amount offered. It’s another sign that demand for high-quality corporate paper is there.
Treasuries got their safe-haven bid on Thursday, pulling the 10-year back from its October high.
Friday’s jobs report is the next test. Economists expect 65,000 new jobs, a 4.2% unemployment rate and 0.3% wage growth.