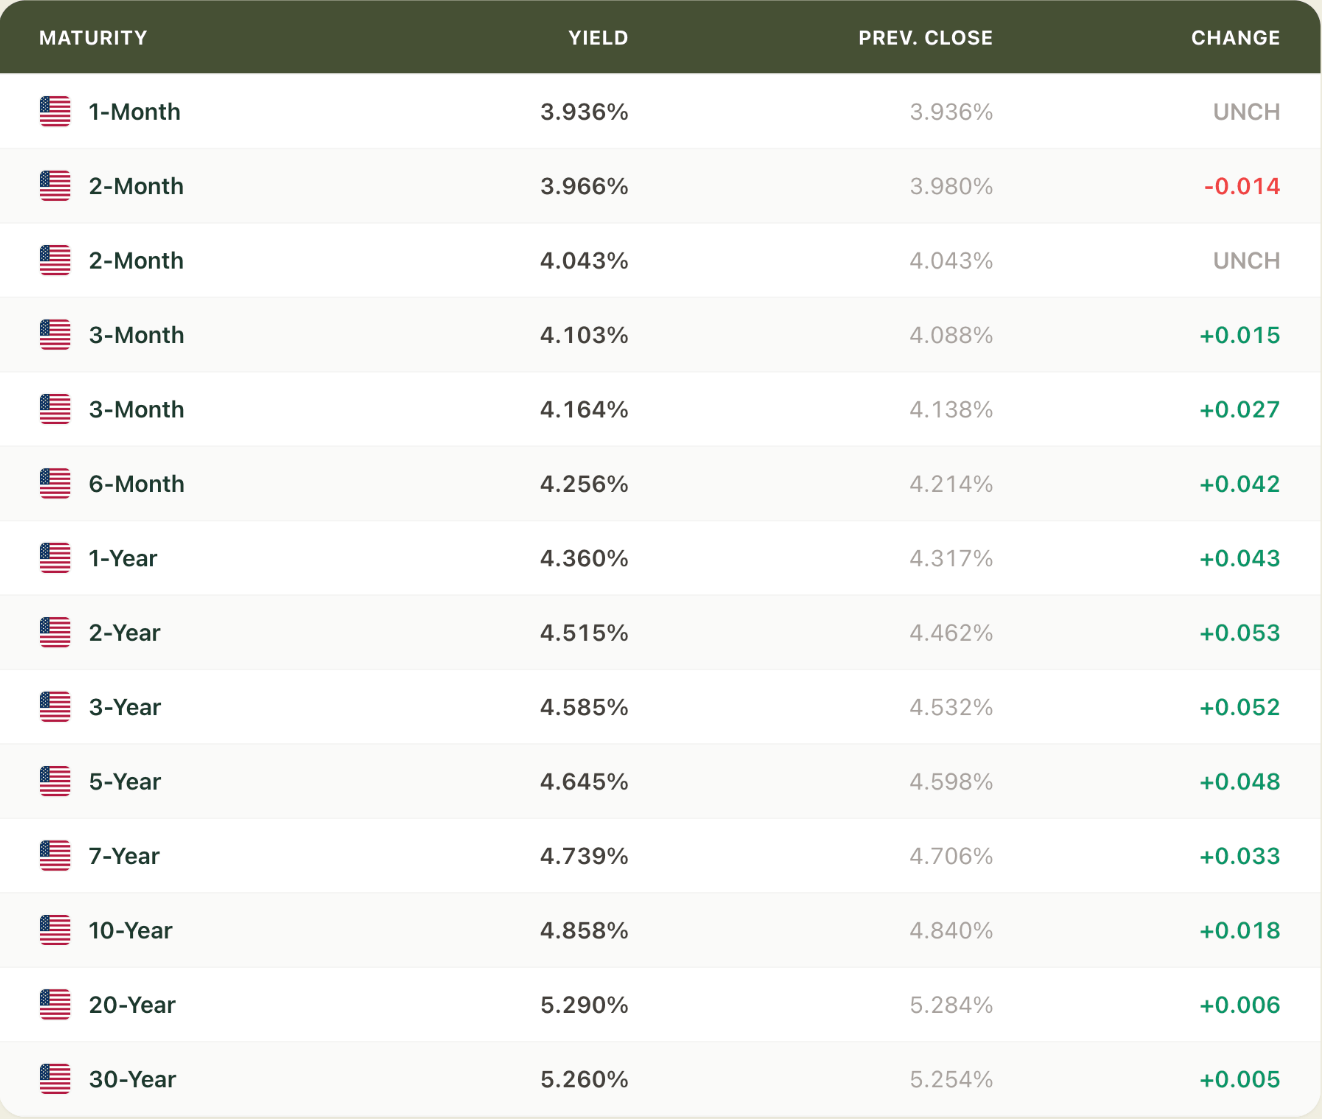
Even with today’s losses in shorter maturities, bonds recorded their fifth consecutive weekly gain, and yields ended the week lower across the curve. A much stronger jobs report is keeping the market fairly certain the Fed will raise rates in December.
Stronger than expected jobs numbers
October nonfarm payrolls rose 165,000, far above the 65,000 forecast. Private payrolls rose 159,000 against an expected 50,000.
September was revised up to 60,000 from 29,000 and August to 186,000 from 133,000. The three-month average rose to 137,000 from 79,000.
The unemployment rate fell to 4.1% from 4.2%, though the broader U6 measure rose to 7.9% from 7.6%.
Average hourly earnings rose 0.4%, above the 0.3% forecast. Over 12 months they’re up 3.1%, down from 3.2%.
The labor force participation rate rose to 61.9% from 61.8%.
Fed expectations keep shifting
Rate-hike expectations ticked up after the report. San Francisco Fed President Daly, a 2027 FOMC voter, said she expects additional policy tightening. That follows Richmond Fed President Barkin’s comments on gradual hikes. Abroad, Bank of England Governor Bailey said another rate hike is possible if energy prices stay high.
Consumers: Sentiment up, Credit up
Sentiment: The preliminary University of Michigan reading for November rose to 51.0 from 48.0, beating the 47.2 forecast. Cost-of-living concerns remain the biggest weight.
Credit: Consumer credit jumped $27.8 billion in September against a forecast of $11 billion, with revolving credit up $16.3 billion.
WTI rose 0.4% to $90.88 but still fell more than $13 a barrel for the week.
The Dollar Index jumped 0.7% to 102.28, up 0.3% on the week. EUR/USD fell 0.7% to 1.1139, and USD/JPY rose 0.5% to 156.51.
Gold fell 0.9% to $4,075.80.
Copper slipped 0.5% to $6.24.
The week ahead
Monday: $58 billion 3-year note auction.
Tuesday: October CPI is expected at 0.3% (prior 0.6%) with core at 0.2%, followed by a $42 billion 10-year auction.
Wednesday: The Treasury market is closed for Veterans Day.
Thursday: Jobless claims, existing home sales and a $25 billion 30-year bond auction.
Friday: October PPI, expected at 0.3% after a 1.3% prior reading.
Bonds have now rallied for five straight weeks.
The economy added jobs faster than expected, wages are still rising, and the market is pricing a December hike.
Next week’s CPI and three Treasury auctions will play a big role in keeping the streak alive.