The week started with losses in shorter tenors, but the long end refused to budge.
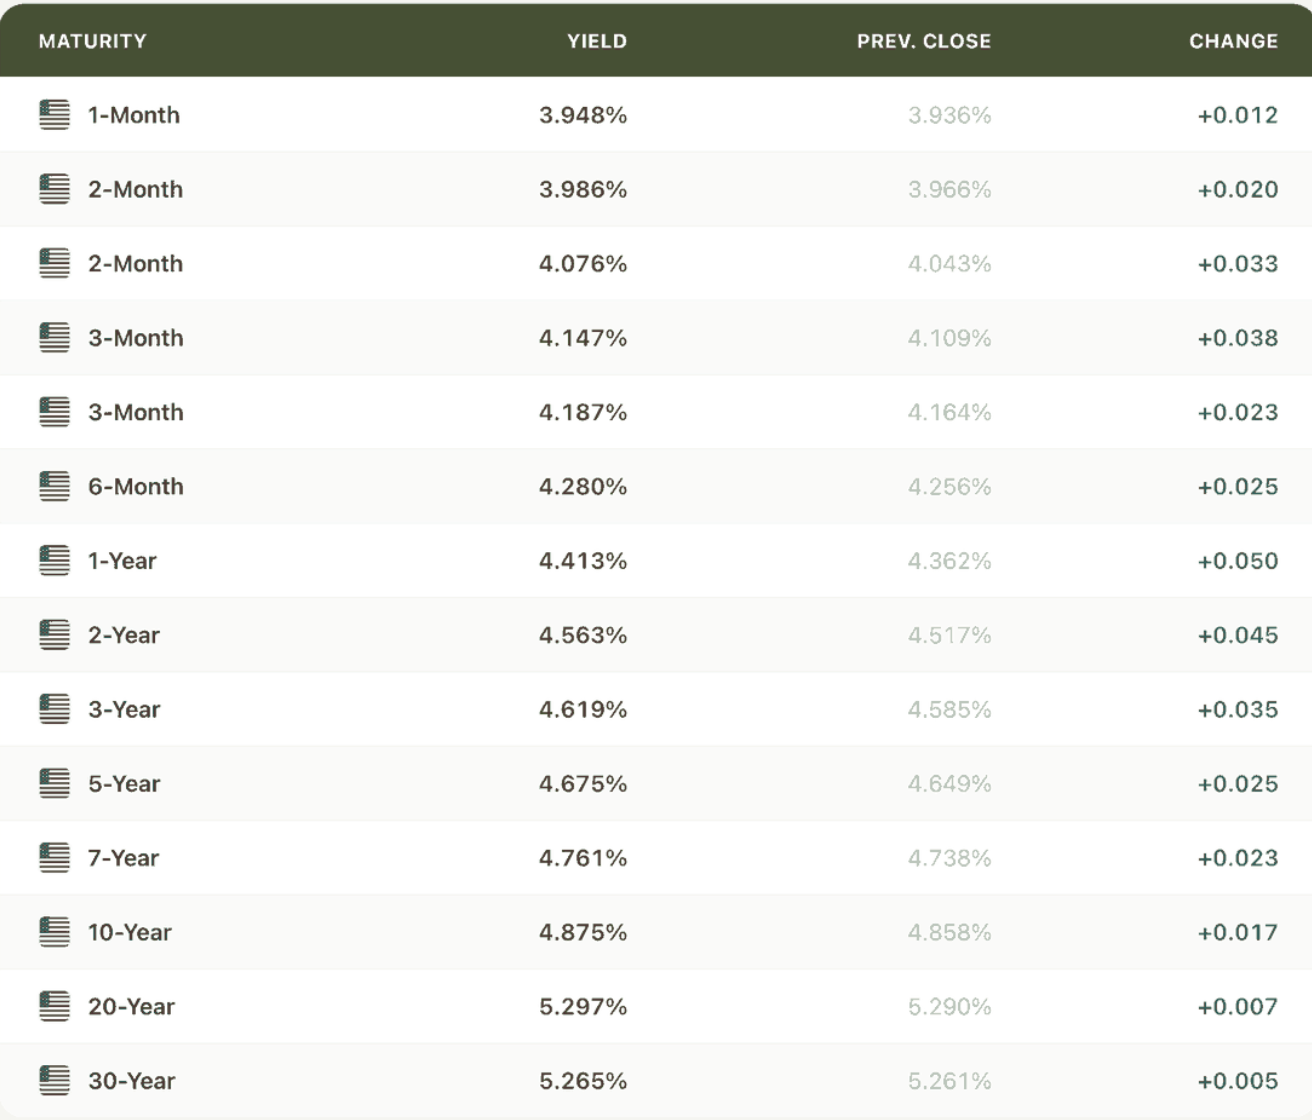
The 30-year closed unchanged at 5.26%, right where it finished Friday, while the 2-year rose 3 basis points to 4.56%. The 10-year ended at 4.86%, up 1 basis point.
Treasuries opened with modest gains and tried an early push higher. That move ran into resistance as equities opened strong after last week’s volatility, and shorter tenors led the way lower.
The front end took more pressure in morning trading, and buyers eventually showed up shortly after the 2-year yield moved above Friday’s high.
The 3-year auction showed weak demand
The $58 billion 3-year note auction drew soft demand, and the market held its ground anyway.
The high yield was 4.627%, well above the prior 12-auction average of 3.952%. Bid-to-cover came in at 2.53, below the 2.66 average. Indirect bidders took 55.5%, down from 63.4%, while direct bidders took 35.0%, up from 24.6%.
Treasuries stayed above their late-morning lows into the close and caught a small bid late.
Other markets
Commodities: Gold rose 1.0% to $4,115 an ounce and copper rose 1.8% to $6.35 a pound.
Currencies: EUR/USD rose 0.7% to 1.1222 and GBP/USD rose 0.7% to 1.3440. USD/JPY fell 0.4% to 157.76, and USD/CNH was unchanged at 6.6694.
Economic data and news
New York Fed survey: The October Survey of Consumer Expectations showed no change in inflation expectations, at 3.9% for one year, 3.3% for three years and 3.0% for five years. Expectations for higher unemployment a year from now rose to a level not seen since April 2020.
GDPNow: The Atlanta Fed’s Q4 GDP estimate rose to 3.5% from 3.4%.
Wholesale inventories: Inventories rose 0.7% in September, against the 0.6% consensus. August was revised up to 0.6% from 0.5%.
China: The extension of the suspension of additional 24% tariffs on U.S. goods runs another two months. Consumer prices were unchanged from September (+0.7% from a year ago) and producer prices rose 5.7% from a year ago, above the 5.3% expected.
Japan: The September Coincident Indicator rose 0.7% month over month, while the Leading Index fell to 116.4, below the 116.7 expected.
Eurozone and Germany: November Sentix investor confidence was 2.4, above the 2.1 expected. Germany’s September trade surplus was EUR 15.6 billion, below the EUR 19.2 billion expected.
Australia: September building approvals rose 5.1% month over month, in line with expectations.
Overall, it was a mixed start to the week, with the front end heavier and the long end steady.
Tomorrow’s October CPI is the main event, with the consensus at 0.3% for the headline and 0.2% for core. A $42 billion 10-year note auction follows at 1:00 p.m. ET.