Apple has about $137 billion in cash and securities, and it just went out and borrowed $7.5 billion.
What Apple sold
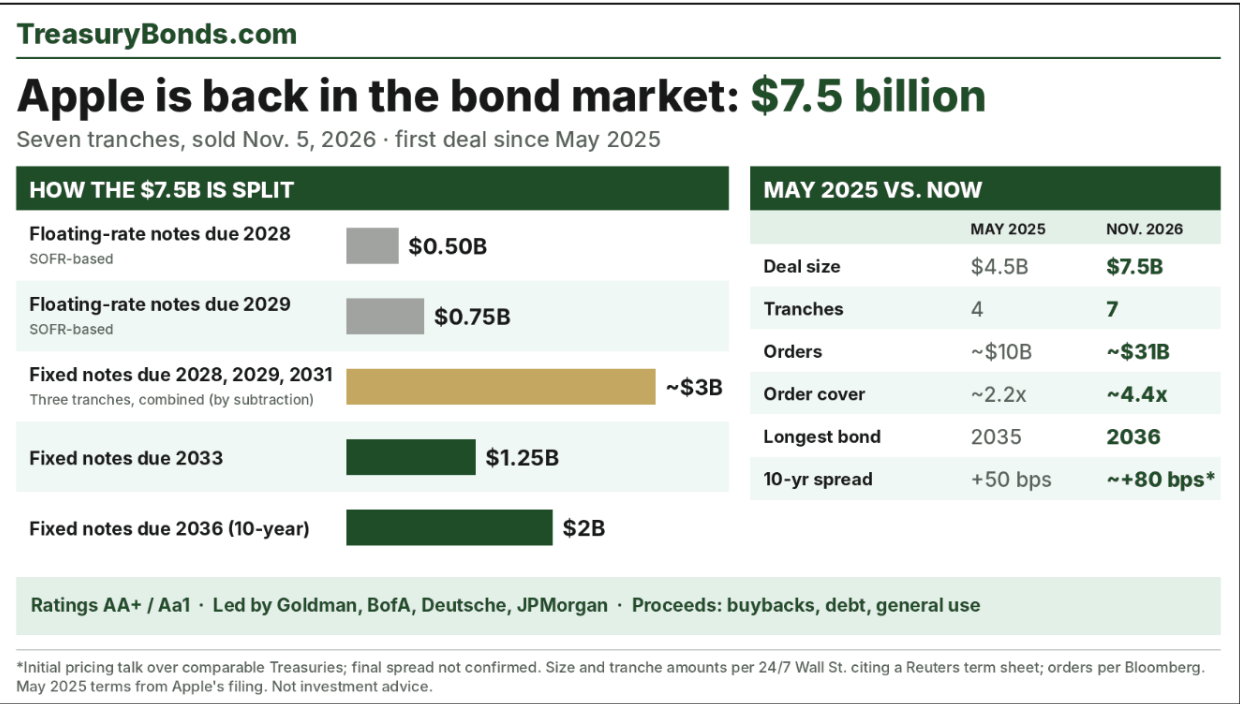
Apple’s first bond deal since May 2025 came in seven parts on Nov. 5. It started as “about $7 billion” and, according to a term sheet reported by Reuters, ended at $7.5 billion.
Two floating-rate notes: $500 million due 2028 and $750 million due 2029, priced off SOFR.
Five fixed-rate notes: due 2028, 2029, 2031, 2033 and 2036. The 2033s were $1.25 billion and the 10-year 2036s were $2 billion, which leaves about $3 billion for the other three.
Coupons: fixed coupons running from 4.65% on the shortest to 5.35% on the 10-year.
The demand was big
Bloomberg reported about $31 billion of orders, roughly 4.4 times the amount for sale. Compare that with May 2025, when Apple sold $4.5 billion against about $10 billion of orders, or about 2.2 times.
Spreads are wider than last spring
Initial pricing talk was about 45 basis points over Treasuries on the shortest fixed note, widening to about 80 on the 10-year. In May 2025, Apple’s 10-year-style note priced at +50.
Why this one is different
Microsoft, Oracle, Meta and Alphabet have all been in the market in the past couple of weeks, largely to fund AI spending. Apple’s filing points to buybacks and repaying debt instead. The Nov. 2 earnings call also had a notable line: the CFO said Apple is “no longer using net cash neutral as a target.” That suggests Apple may be comfortable carrying more debt than before.
Bottom line
Apple didn’t need the money, and investors showed up anyway with more than four times the amount on offer. Very large corporate borrowers can now raise debt at spreads well above where they sat last spring.