After five straight weekly gains, Treasuries took a beating this week.
Yields rose across the curve on talk that the Fed might raise rates by 50 basis points in December, and a hot inflation backdrop didn’t help.
The 10-year finished Friday at its highest settlement in more than four weeks.
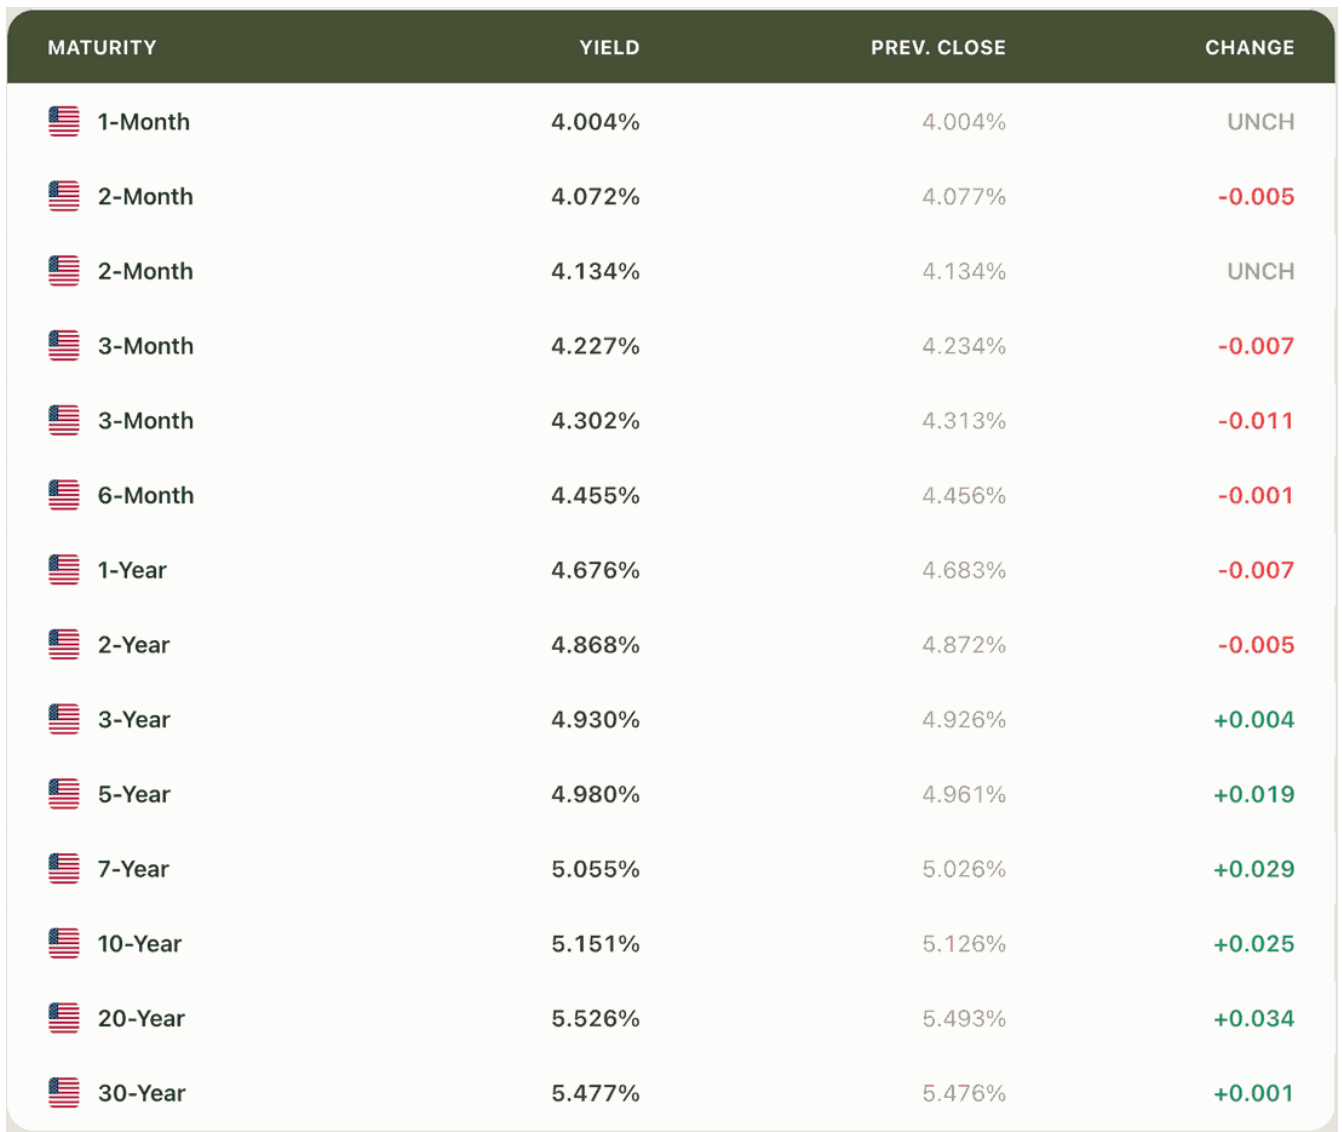
The front end did better on Friday after Thursday’s underperformance.
The 2-year closed seven basis points below its 2026 high of 4.96%, set in late September.
Why yields climbed
The October Producer Price Index was the main story Friday. The headline rose 0.3% on the month, a touch below the 0.4% consensus, and core also rose 0.3%, as expected.
But September was revised up to 1.4% from 1.3%, and core to 0.8% from 0.7%.
On a yearly basis, producer prices are up 6.5%, the largest increase since November 2022, and core is up 5.0%.
The takeaway: wholesale inflation is still a big problem, and the report is no source of comfort.
The New York Fed’s Williams and the Chicago Fed president both said the central bank has more work to do. Williams also said there is time to gather more information and that longer-term inflation expectations remain anchored.
Dollar, oil and the rest of the market
The Dollar Index rose 0.2% to 103.40, its highest level since early April, and gained 1.1% for the week.
USD/JPY was unchanged at 159.80, just below 160.
WTI crude fell 0.4% to $88.46 a barrel, and finished the week down about $1.50.
Gold was unchanged at $3,886.20 and copper fell 1.8%.
Global backdrop
China: October new loans were negative, at CNY-100.0 billion versus an expected CNY80.0 billion. Total social financing was CNY1,150.0 billion versus an expected CNY1,420.0 billion.
Europe: Eurozone Q3 GDP grew 0.4% on the quarter. Germany plans to borrow more than EUR200 billion in 2027, the second-highest annual total since World War II.
Japan: Prime Minister Takaichi is reportedly leaning against a tax increase to fund defense spending.
The week ahead
Monday: Empire State Manufacturing
Tuesday: October Retail Sales (consensus 0.3%, prior 0.8%), import prices and industrial production
Wednesday: Housing starts, a $16 billion 20-year bond auction and the October FOMC minutes at 2:00 p.m. ET
Thursday: Jobless claims and the Philadelphia Fed survey
Friday: Final University of Michigan sentiment
What this could mean for fixed income investors
Rate-hike talk is hurting bond prices across maturities, so longer and shorter holdings both lost ground this week.
Higher yields mean new money can lock in more income, but prices could fall further if inflation data keeps surprising to the upside.
Pay attention to the FOMC minutes and Tuesday’s retail sales. They could move rate-hike expectations in either direction.
The 20-year auction on Wednesday will show how much demand there is for long bonds at these yields.
A stronger dollar and weak Chinese credit data point to uneven global growth, which can pull yields in different directions.
Bottom line
Yields rose 22 to 36 basis points this week, and Friday’s inflation data gave bond investors little reason to expect relief soon. Next week’s minutes, retail sales and auction should show how far the market believes the Fed will go.