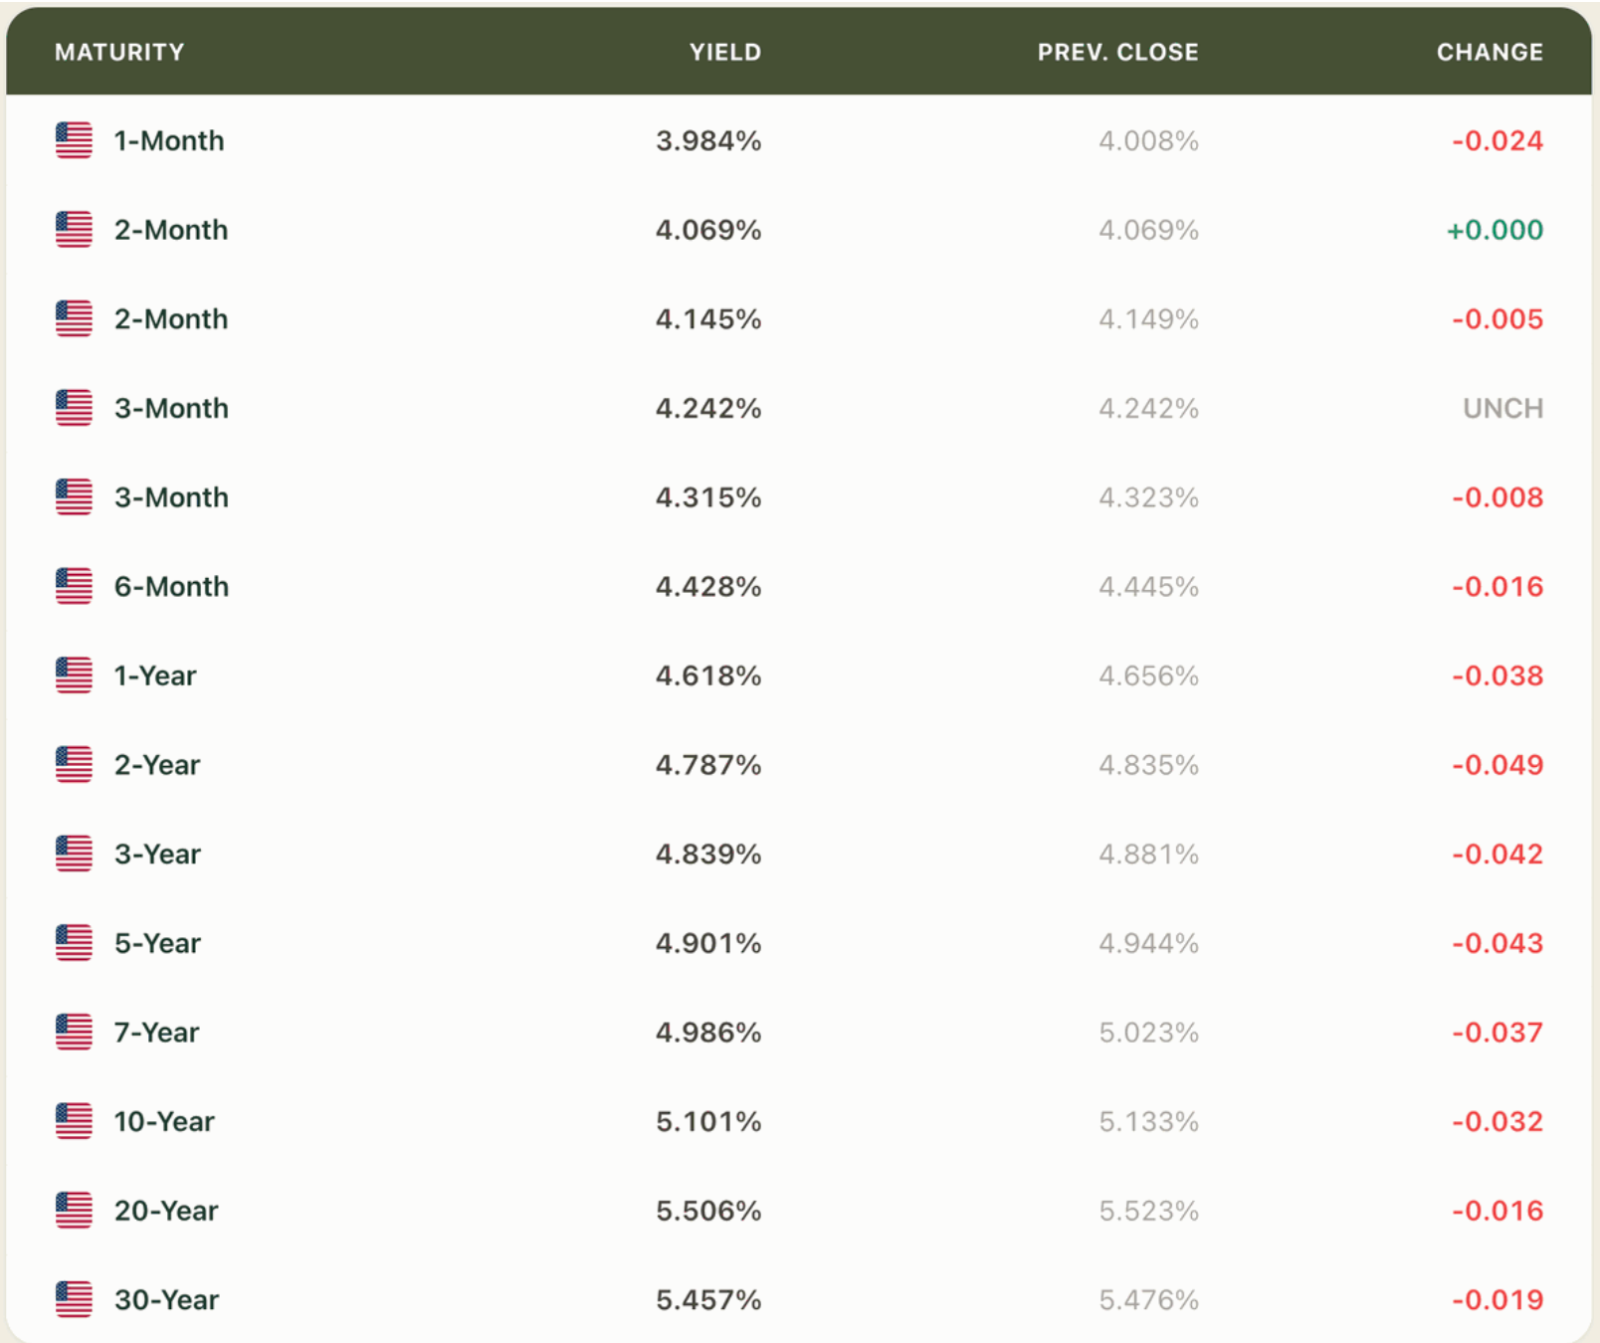
Treasuries rebounded again on Tuesday. They shrugged off early selling after the day’s data showed prices still rising in October’s import, export, and retail sales numbers.
Selling stopped when yields approached Monday’s intraday highs, and prices climbed as stocks weakened.
The 5- and 10-year yields moved back toward their 50-day moving averages, which they had climbed above during last week’s selloff.
The Data
Retail sales rose 0.2% in October (consensus 0.3%) after 0.8% in September. Excluding autos, they jumped 0.6% against a 0.1% forecast, and September was revised up to 1.1%. The notes say the gain was mostly price increases, not stronger demand.
Import prices rose 1.1% in October. Excluding oil, they were up 0.8%, after a revised 0.5% in September. Export prices rose 1.1%.
Industrial production fell 0.4% (consensus +0.1%), and capacity utilization slipped to 76.4%. The notes say the drop came from mining and utilities, not manufacturing.
The NAHB housing index fell to 25 in November, below the 29 consensus.
The Atlanta Fed’s GDPNow estimate for Q4 growth rose to 3.5% from 3.4%.
Markets
Oil: WTI rose 0.3% to $86.02 but ran into resistance at its 200-day moving average (88.06) and gave back most of its gains.
Dollar: The U.S. Dollar Index slipped 0.1% to 103.48, below its best level since April 2025.
Gold: +0.3% to $3,864.40.
Copper: -0.3% to $5.99.
Currencies: EUR/USD +0.1% to 1.1006, GBP/USD +0.2% to 1.3212, USD/JPY -0.1% to 159.36.
Global Headlines
Japan’s Ministry of Finance will postpone the launch of a new floating-rate 2-year JGB.
Germany’s Finance Ministry backed Pablo Hernandez de Cos to lead the European Central Bank and proposed Markus Brunnermeier as chief economist.
Italy’s October CPI rose to 5.5% year over year from 4.2%.
U.K. unemployment fell to 4.6%, with employment up 156K and wage growth slowing.
Germany’s ZEW sentiment jumped to 35.6, well above the 28.8 forecast.
The Fixed Income Playbook
Price gains in import, export and retail data, plus Italy’s jump, keep rate worries alive even as bonds rally.
Yields found buyers near key levels, and weaker stocks helped.
Watch the 50-day moving averages. 5- and 10-year yields are back near those levels, and a break either way could set the next move.
Mixed growth data cuts both ways. Soft industrial output and housing help bonds, but a firm GDPNow estimate and strong retail ex-autos argue against big yield drops.
Wednesday is event-heavy. The FOMC minutes, a 20-year bond auction and housing data are all on the calendar.
Bottom Line
Treasuries extended last week’s rebound, with yields down 1 to 4 bps, even though the day’s data showed inflation pressure persisting. Wednesday’s Fed minutes and 20-year auction are the next tests.