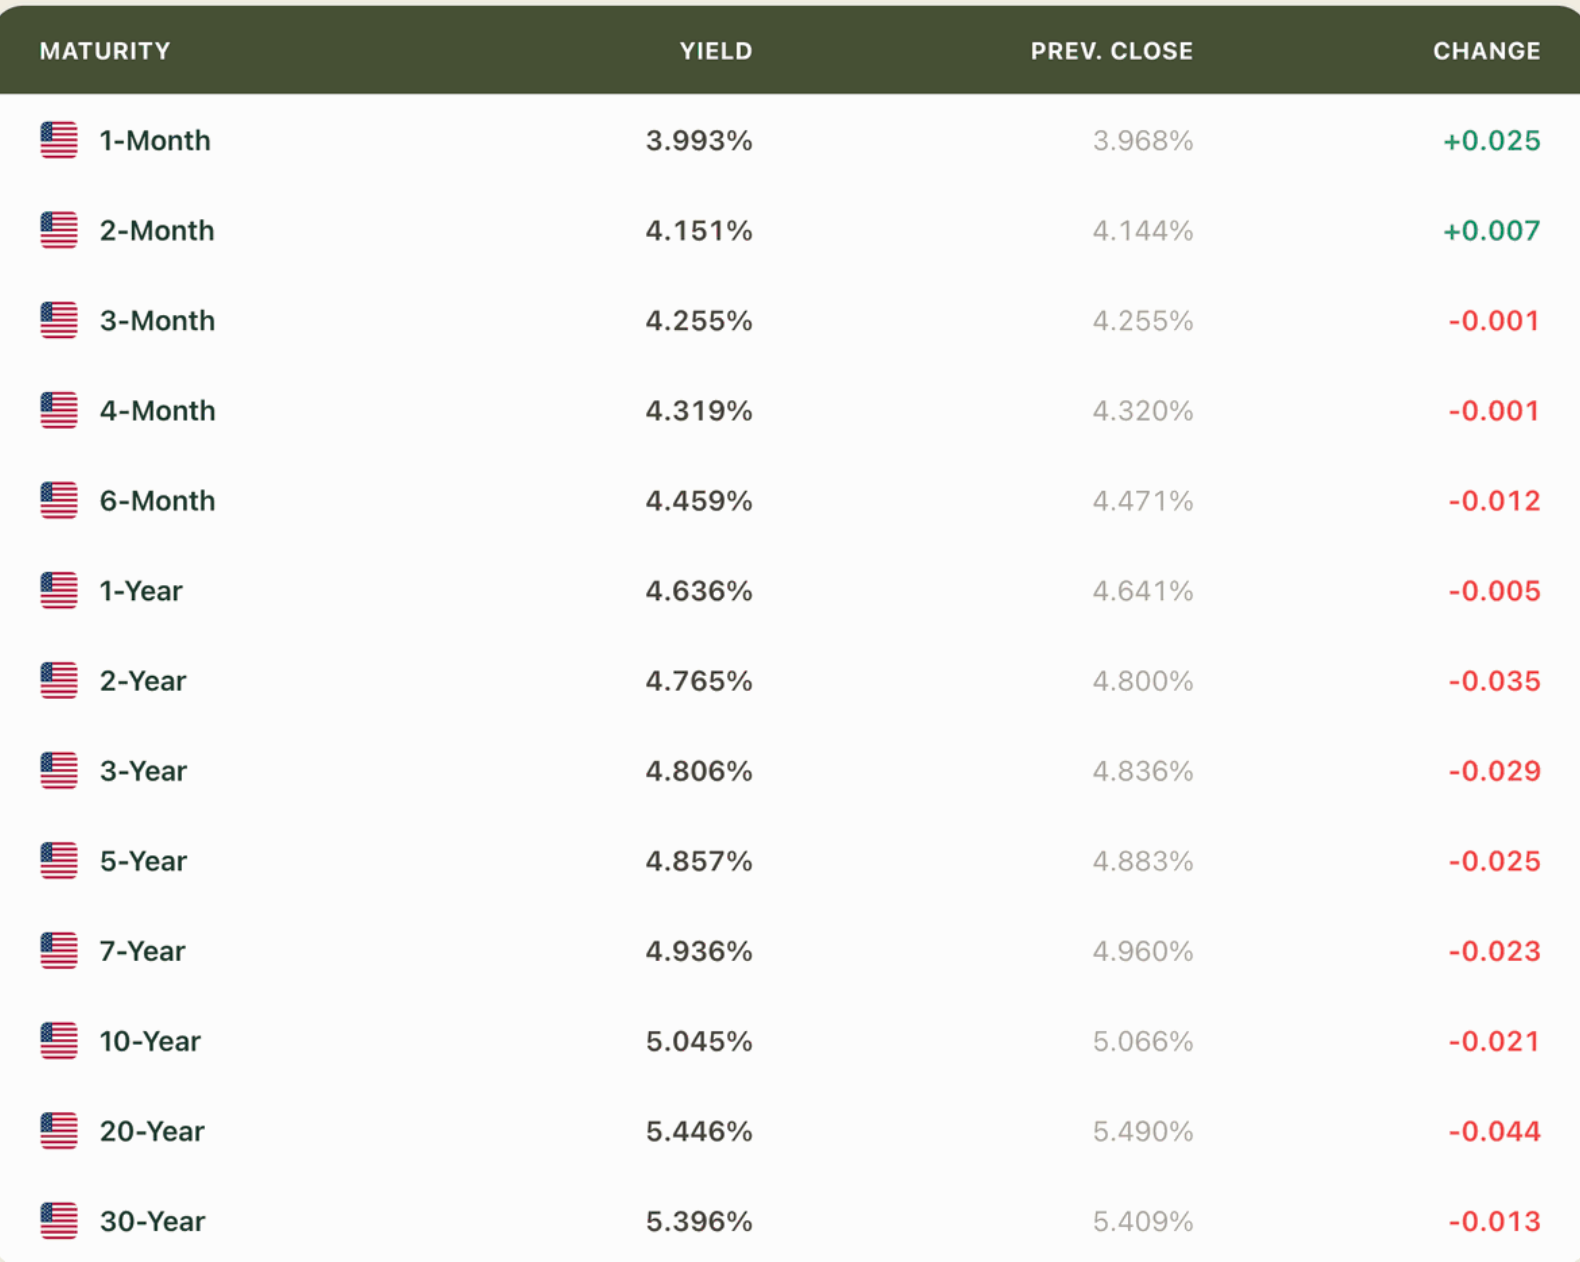
Treasuries had a quiet Thursday. Yields ended the day slightly lower and below their 50-day moving averages across the curve.
The session started weak. Overnight, U.S. equity futures jumped ahead of Anthropic’s Nasdaq debut, and bonds sold off. Then the jobless claims report came out, buyers stepped in, and yields moved back to where they started.
Stocks gave up their early gains and the bond market kept its bid. Treasuries hit session highs in the early afternoon and pulled back a bit late. A last push into the close left 5s, 10s and 30s all below their 50-day averages.
The Labor Market Is Showing a Crack
Initial jobless claims for the week ending Nov. 14 rose by 1,000 to 203,000. The consensus was 199,000.
The bigger number was continuing claims, which jumped by 70,000 to 1.763 million, a ten-week high.
Fewer people are being laid off, but the ones who are laid off are taking longer to find new work.
That tends to show up in the economy later than the headline claims number does.
Other data was soft too. The Conference Board’s Leading Index fell 0.3% in October. The consensus was a 0.1% gain, and September was flat.
What Else Moved
WTI crude was unchanged at $83.29 a barrel after a small intraday rally faded.
The U.S. Dollar Index set a new high for the year, then slipped back to 103.91.
Gold fell 1.5% to $3,686 an ounce and copper fell 0.7% to $5.63 a pound.
Overseas
Australia: unemployment rose to 4.9% (expected 4.7%) and employment fell by 43,500 jobs. That led to early speculation the Reserve Bank of Australia could cut rates.
Indonesia: Bank Indonesia surprised the market by raising its policy rate 25 bps to 6.00%.
Europe: ECB policymaker Moulin said inflation is still too high but that second-round effects aren’t showing up. That’s a common view among his peers.
Japan: September core machinery orders fell 0.3% m/m (expected +1.3%).
New Zealand: the October trade deficit widened to NZD 2.772 bln.
Switzerland: the October trade surplus rose to CHF 4.089 bln.
U.K.: the November CBI industrial orders balance was -12 (expected -29).
What This Could Mean for Fixed Income Investors
The 10-year at 5.05% is still historically high for investors who want income.
Yields finishing below their 50-day averages is notable, but it’s an area the market has crossed back and forth this week.
The curve is still positively sloped. The 2-year is 4.78% and the 30-year is 5.40%, about 62 bps apart.
The Day Ahead
Final University of Michigan consumer sentiment for November comes out at 10:00 ET. The consensus is 51.0, the same as the prior reading.