Treasuries ended the week on a strong note. It was a big bounce, and it came from a flight to safety.
The Day in Treasuries
Friday extended the rebound off the November lows reached a week ago.
The main driver was weakness in technology stocks, which pushed the Nasdaq into negative territory for 2026 and led to selling in other parts of the equity market.
Precious and industrial metals also came under pressure.
Silver and gold futures fell to levels last seen in September 2025, and copper extended its reversal from a record in September, dropping to late-March levels.
Treasuries benefited from the selling.
Why Short Bills Didn’t Join the Rally
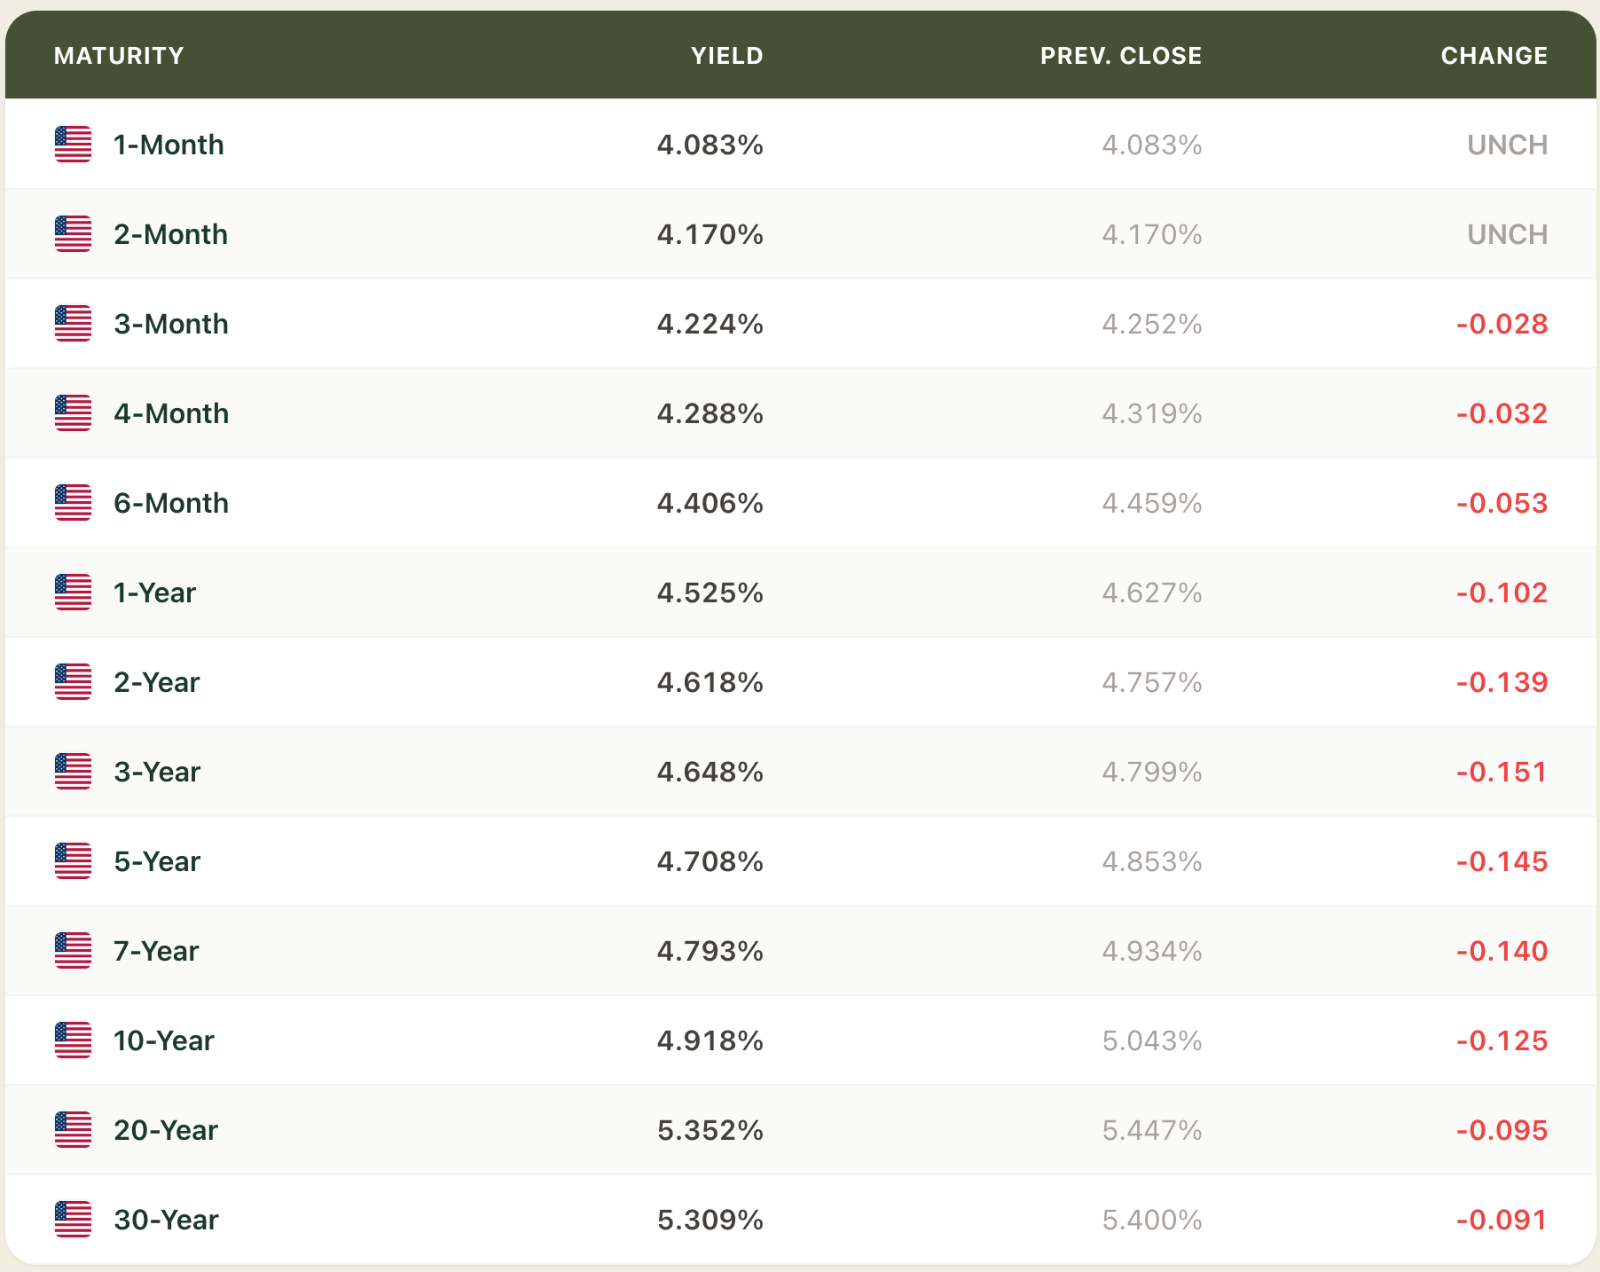
Four- and eight-week bills didn’t benefit.
They added to Thursday’s losses because the benchmarks for those yields mature after the December FOMC meeting.
That meeting is still expected to produce a 25-basis-point rate hike, although the implied probability dropped to about 92% from 100% yesterday and a week ago.
Fed Governor Cook, an FOMC voter, voiced continued support for higher rates.
Bank of England policymaker Greene said the central bank’s duty is to anchor elevated inflation expectations, and that the risk of not doing enough exceeds the risk of doing too much.
Consumer Sentiment
The final University of Michigan sentiment index for November rose to 51.5, above the 51.0 consensus and the preliminary 51.0. October’s final reading was 48.0, and the index stood at 51.0 a year ago. Cost-of-living concerns are still the biggest issue weighing on sentiment, though inflation expectations improved around the election. Interviews were conducted between Oct. 20 and Nov. 16.
Commodities and Currencies
WTI crude rose 1.0% to $84.09 a barrel. It briefly touched its lowest level since late August before reversing, trimming this week’s loss to just over $4.
Gold fell 4.7% to $3,514.50 an ounce.
Copper fell 2.7% to $5.48 a pound.
The U.S. Dollar Index slipped 0.1% to 103.80, trimming this week’s gain to 0.4%. It remains just below its highest level since April 2025.
USD/JPY fell 0.8% to 158.47, and USD/CNH fell 0.2% to 6.6758. EUR/USD was unchanged at 1.0968 and GBP/USD was unchanged at 1.3084.
News and Global Data
China: The People’s Bank of China left its one-year and five-year loan prime rates at 3.00% and 3.50%, as expected. October foreign direct investment was -2.4% (prior -4.3%).
Japan: October national CPI was +2.3% y/y (prior +2.1%). Core CPI was +2.2% y/y, just below the +2.3% expected.
U.K.: October retail sales rose 0.7% m/m (expected 0.0%). Core retail sales rose 0.9% m/m (expected -0.1%). October public sector net borrowing was GBP 17.0 bln (expected GBP 18.0 bln).
Germany: October PPI rose 1.4% m/m (expected +0.9%) and 8.1% y/y (expected +7.2%).
Elsewhere: Hong Kong’s October CPI was +2.2% y/y. India’s October infrastructure output rose 10.9% y/y, and its FX reserves fell to USD 705.34 bln from USD 719.55 bln.
The Playbook for Fixed Income Investors
Even after this week’s drop, the 10-year at 4.91% and the 30-year at 5.30% offer considerable income.
The market pulled back from fears of a 50-basis-point move, but the odds of a 25-basis-point increase remain around 92%.
The Week Ahead
Monday: flash November S&P Global manufacturing PMI (prior 54.9) and services PMI (prior 56.1) at 9:45 ET, and $69 bln 2-year note auction results at 13:00 ET.
Tuesday: FHFA and Case-Shiller home prices at 9:00 ET, November consumer confidence (consensus 92.0) at 10:00 ET, and the $70 bln 5-year note auction results at 13:00 ET.
Wednesday: a heavy data day at 8:30 ET, including the second estimate of Q3 GDP (consensus 3.4%), October personal income and spending, PCE and core PCE prices (both consensus 0.3%), durable orders and weekly jobless claims (consensus 200,000). Later come new home sales at 10:30 ET, the $44 bln 7-year note auction results at 13:00 ET and the November Beige Book at 14:00 ET.
Thursday: bond and equity markets are closed for Thanksgiving.
Friday: October advance trade in goods, retail inventories and wholesale inventories at 8:30 ET.
Bottom Line
A flight to safety gave Treasuries their best week in a while, with the 10-year yield back below 5%. The market still expects the Fed to raise rates in December, so the picture isn’t simple. The data and auctions ahead of Thanksgiving, especially Wednesday’s PCE report and the 2-, 5- and 7-year note auctions, could determine whether this bounce continues.